Tag: mortgage advice

  • Buy-to-Let Watch: Addressing Tenant Fraud Challenges

    Buy-to-Let Watch: Addressing Tenant Fraud Challenges

    Tenant fraud is becoming a significant issue for buy-to-let landlords in the UK, with recent research revealing that it costs them an estimated £266 million each month. This alarming trend highlights the urgent need for landlords and brokers to be vigilant in their tenant screening processes.

    TL;DR: Tenant fraud is costing UK landlords £266 million monthly; with a 140% increase in detected fraud cases, landlords must enhance their tenant verification methods.

    How Has Tenant Fraud Increased Recently?

    Research conducted by Goodlord indicates a troubling rise in tenant fraud, with detected cases increasing from just over one per 1,000 tenancy applications in 2022 to 2.9 per 1,000 in 2023. This represents a staggering 140% year-on-year increase. The most common method employed by fraudsters involves the use of doctored bank statements, with fake documents constituting 94% of all fraud cases. The Cifas Fraudscape 2026 report corroborates these findings, noting that over 444,000 cases were recorded in 2025, marking the highest annual total to date.

    What Are the Implications of the Renters’ Rights Act 2025 for Buy-to-Let Landlords?

    The introduction of the Renters’ Rights Act 2025 has heightened the stakes for landlords. With the abolition of Section 21, landlords can no longer regain possession of their properties without a specific legal ground. Additionally, notice periods under Section 8 have been extended, sometimes up to four months. This legislative change means that landlords must be more proactive in their tenant vetting processes to avoid potential losses due to fraud.

    What Should Landlords and Brokers Do About Buy-to-Let Fraud?

    Landlords and brokers should incorporate discussions about tenant fraud into their advisory conversations. Understanding the risks associated with fraudulent applications is important for protecting investments. While there is a legal route available for landlords through Ground 17 of the Housing Act, which addresses tenancies obtained through false statements, this process is discretionary and requires substantial evidence, making it far from a guaranteed solution.

    Recent research indicates that around 20% of landlords have reported being victims of illegal subletting, while 8% have encountered fake financial information from prospective tenants. Brokers who are equipped with knowledge about these issues can better assist their clients in navigating the complexities of tenant fraud.

    What This Means for Buy-to-Let Landlords

    For landlords, the rise in tenant fraud poses a significant risk to their financial stability. With the inability to swiftly regain possession of properties and the increasing prevalence of fraudulent applications, it is imperative for landlords to implement robust tenant screening processes. This includes verifying financial information and conducting thorough background checks. By doing so, landlords can mitigate potential losses and ensure their investments are safeguarded.

    Frequently asked questions

    What are the most common tactics used in tenant fraud?

    Doctored bank statements are the most prevalent method, with 94% of fraud cases involving fake documents. This highlights the importance of thorough verification processes for landlords.

    How can landlords protect themselves from tenant fraud?

    Landlords can protect themselves by implementing stringent tenant screening processes, including verifying financial information and conducting comprehensive background checks to identify potential fraud.
  • Improving the Mortgage Market: Lender Collaboration Insights

    Improving the Mortgage Market: Lender Collaboration Insights

    The latest findings from the annual Lender Collaboration Survey highlight significant delays in property transactions, impacting the mortgage market. Many firms are facing issues that could hinder completion times, ultimately affecting client satisfaction and the home buying process.

    TL;DR: Many firms report transaction delays affecting completion times; clearer guidance and a common referral platform could streamline the mortgage process.

    What are the main findings of the Lender Collaboration Survey?

    The Lender Collaboration Survey reveals that discussions between conveyancers and lenders often take longer than expected, leading to delays in property transactions. These delays can create a ripple effect, influencing client expectations and the overall experience of moving home. The survey indicates that many firms are experiencing challenges that could be mitigated through better communication and collaboration.

    Why are delays occurring in the mortgage market?

    Delays in the mortgage market are primarily due to a lack of clear guidance on common scenarios faced by conveyancers and lenders. When conveyancers are unsure about how to proceed, they often refer cases back to lenders, which consumes time and resources. This not only prolongs the transaction process but also adds to the frustration of clients awaiting their home purchases.

    What solutions are being proposed to speed up transactions?

    To address these delays, the survey suggests that working with UK Finance to establish clearer, less ambiguous guidance could significantly streamline the process. By reducing unnecessary referrals, conveyancers would gain confidence in their decisions, allowing them to proceed without waiting for lender input on routine queries. Additionally, the adoption of a common referral platform, such as Lender Exchange or LMS, is recommended to create consistency across the market and eliminate duplication of efforts.

    What does this mean for mortgage borrowers and brokers?

    For mortgage borrowers and brokers, the implications of these findings are substantial. Delays in property transactions can lead to increased anxiety for buyers and sellers alike, affecting their plans and financial arrangements. By advocating for clearer guidelines and a unified referral system, brokers can help facilitate smoother transactions, ultimately enhancing the home buying experience for their clients. Staying informed about these developments will be important for all stakeholders in the mortgage market.

    Frequently asked questions

    How can delays in property transactions affect buyers?

    Delays can lead to increased stress for buyers, potentially causing them to miss out on properties or incur additional costs, such as extended rental agreements or storage fees.

    What should brokers do to navigate these delays?

    Brokers should stay updated on industry developments and advocate for clearer communication between lenders and conveyancers to help expedite transactions for their clients.

  • Unregulated Mortgage Advice: Risks in the Mortgage Market

    Unregulated Mortgage Advice: Risks in the Mortgage Market

    Recent findings reveal that a significant number of UK borrowers are turning to unregulated sources for mortgage advice, raising concerns about the potential risks involved. With many people relying on informal guidance, the implications for the mortgage market could be profound, particularly for those making critical financial decisions without adequate oversight.

    TL;DR: A large portion of borrowers are seeking unregulated mortgage advice; this trend poses risks of financial loss, especially among younger consumers.

    Why Are Borrowers Choosing Unregulated Advice?

    A survey of UK credit card holders found that many sought financial guidance from non-regulated sources, with mortgages being a key area of concern. The trend is particularly pronounced among younger consumers, highlighting a growing reliance on informal advice that could have serious implications for borrowers navigating the complexities of the mortgage market.

    What Are the Risks of Unregulated Mortgage Advice?

    The survey also revealed alarming statistics regarding financial losses incurred from poor advice. Many credit card holders reported losing money due to bad guidance, with some experiencing notable losses in the past year. For mortgage-related decisions, the stakes are even higher, as the most common loss range among affected consumers was significant. This raises critical questions about the reliability of the advice being sought and the potential financial repercussions for borrowers.

    How Are Consumers Using AI for Financial Advice?

    Interestingly, a portion of consumers reported using AI tools for financial advice, covering areas such as budgeting and investing. However, a study assessing major AI platforms indicated that many users fail to verify the guidance received. A significant percentage of respondents did not check the risks associated with the advice, while only a small fraction would verify a financial professional’s credentials. This lack of due diligence could exacerbate the risks associated with unregulated advice.

    What This Means for Borrowers and the Mortgage Market

    The increasing reliance on unregulated advice poses significant risks for borrowers, particularly those new to the mortgage market. For brokers, this trend underscores the importance of demonstrating the value of regulated advice and building trust with clients. As borrowers face potential financial losses from unverified sources, the role of professional guidance becomes even more critical in helping them navigate their mortgage options effectively. For those looking to understand their options better, checking current mortgage rates can provide valuable insights.

    Frequently Asked Questions

    What should I do if I’ve received unregulated mortgage advice?

    If you suspect that you have received unregulated mortgage advice, it’s important to seek a second opinion from a qualified mortgage advisor. They can help assess your situation and provide guidance based on current regulations and best practices.

    How can I ensure I’m getting reliable mortgage advice?

    To ensure you receive reliable mortgage advice, always seek guidance from regulated professionals. Check their credentials and ask about their experience and any potential conflicts of interest before proceeding with their recommendations.

  • House Prices in London Decline Amid Stagnation Elsewhere

    House Prices in London Decline Amid Stagnation Elsewhere

    House prices in London are forecasted to decline further, making it the only region in the UK to experience a drop in property values. The average home in the capital is expected to lose nearly £5,000 by the end of 2026, reflecting a broader stagnation in the housing market across Britain.

    TL;DR: London is the only UK region with falling house prices, projected to drop by £4,766 by December 2026; this impacts homeowners and potential buyers in the capital.

    Why Are House Prices Falling in London?

    According to recent analysis, London has recorded a monthly decline in house prices of -0.2% over the past year. In contrast, other regions, such as the North East, Yorkshire and the Humber, and the North West, have seen positive growth, with the North East leading at 0.8%. The stagnation in London can be attributed to a combination of factors, including rising interest rates and economic uncertainty, which have dampened buyer sentiment.

    How Do Current Trends Compare Across the UK?

    While London faces a downturn, the average monthly house price growth across England stands at 0.3%. The South East has remained flat, but regions like the West Midlands and East Midlands have recorded growth of 0.5%. This divergence indicates that while some areas are stabilising or improving, London is struggling to maintain its value.

    What This Means for Homeowners and Investors

    For homeowners in London, the forecasted decline of £4,766 by December may be concerning, especially as the average property value has already decreased by nearly £21,000 since its peak in July 2025. This trend could influence decisions for potential buyers and investors, who may reconsider entering the London market given the current outlook. Landlords might also need to adjust rental expectations as property values decline.

    Frequently Asked Questions

    What should potential buyers do in a declining market?

    Potential buyers should carefully assess their financial situation and consider waiting for more stable conditions before making a purchase. Monitoring market trends and seeking advice from mortgage brokers can provide valuable insights.

    How can homeowners protect their property value?

    Homeowners can maintain their property value by investing in renovations and improvements, ensuring their home remains appealing in a competitive market. Staying informed about local market conditions can also help in making strategic decisions.

  • Mortgages for Timber-Built Properties: What You Need to Know

    Mortgages for Timber-Built Properties: What You Need to Know

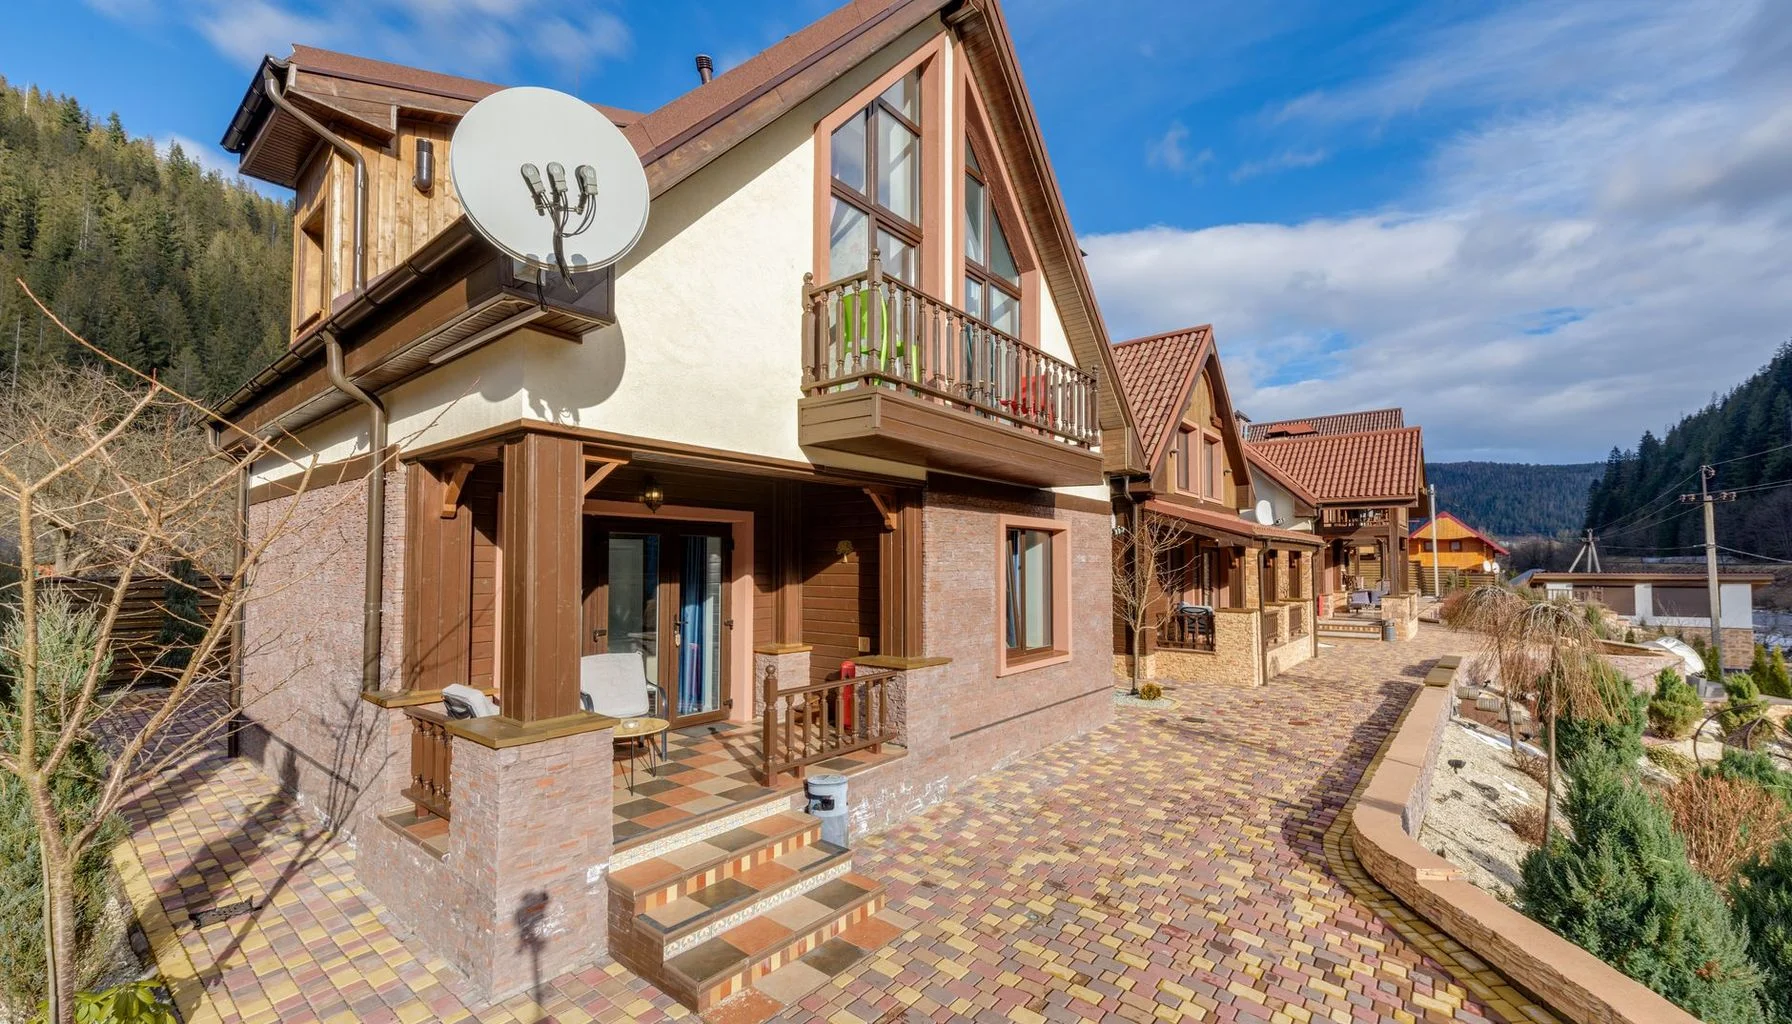
    Obtaining a mortgage on a timber-built property can be challenging, as lenders often have specific concerns regarding these types of constructions. Understanding the nuances of timber properties is essential for potential borrowers and investors.

    TL;DR: Mortgages on timber-built properties are possible but often come with restrictions; fully timber constructions like log cabins face more difficulty in securing standard rates.

    Can You Get a Mortgage on a Timber-Built Property?

    Yes, it is possible to secure a mortgage on a timber-built property, but the options may be limited depending on the construction type. Fully timber homes, such as log cabins, are generally harder to finance compared to properties like Swedish timber or chalet-style homes, which fall under the category of ‘non-standard construction’.

    What Do Lenders Consider?

    Lenders assess several factors when considering a mortgage for timber-built properties:

    • Fire Risk: Timber is more susceptible to fire, which raises concerns for lenders.
    • Durability & Lifespan: The longevity of timber structures can vary, affecting lender confidence.
    • Resale Value: Non-standard constructions may be harder to sell, especially if repossessed.
    • Maintenance Requirements: Timber properties may require more upkeep, influencing lender decisions.

    What This Means for Borrowers

    For borrowers interested in timber-built properties, it is important to understand that high street lenders may not offer standard rates. Instead, you might need to approach building societies or specialist lenders who have more flexible underwriting criteria. Additionally, a larger deposit may be required, and the outcome will heavily depend on the surveyor’s report, the specific construction type, and your financial profile.

    What Should You Do Next?

    If you’re considering purchasing a timber-built property, it’s advisable to consult with a mortgage broker who has access to a wider range of lenders. They can help review your financial situation and the specifics of the property to provide tailored advice. This proactive approach can help you navigate the complexities of securing a mortgage on a non-standard construction.

    Frequently asked questions

    Can I get a mortgage for a log cabin?

    Securing a mortgage for a log cabin can be more difficult due to its classification as a fully timber-built property. You may need to seek specialist lenders.

    What factors influence mortgage approval for timber properties?

    Lenders consider fire risk, durability, resale value, maintenance needs, and the surveyor’s report when assessing mortgage applications for timber properties.

  • Mortgage Vision 2026: Key Insights for Buy-to-Let Investors

    Mortgage Vision 2026: Key Insights for Buy-to-Let Investors

    The UK mortgage sector is gearing up for the Mortgage Vision 2026 roadshow, a pivotal event for buy-to-let investors and mortgage advisers alike. Hosted by Mortgage Brain, this series of events will provide insights into the evolving mortgage market, focusing on opportunities and challenges in the buy-to-let market.

    TL;DR: Registration is now open for the Mortgage Vision 2026 roadshow, which will cover vital topics for mortgage advisers and buy-to-let investors; the event will take place across 12 UK locations, offering insights from industry leaders.

    What is Mortgage Vision 2026?

    Mortgage Vision 2026 is the UK’s leading regional mortgage roadshow, designed to bring together mortgage advisers, lenders, and industry experts. The event spans 12 locations nationwide, aiming to provide practical learning and networking opportunities. It will focus on market insights and the latest innovations affecting the intermediary market, which is particularly relevant for those involved in buy-to-let mortgages.

    Why Should Buy-to-Let Investors Attend?

    For buy-to-let investors, understanding the current mortgage market is important. The roadshow will feature sessions that explore the role of technology, artificial intelligence, and data management in enhancing efficiency and customer outcomes. Investors can gain valuable insights into specialist lending opportunities, which are increasingly relevant in today’s market. With presentations from respected lenders like Fleet Mortgages and Coventry for Intermediaries, attendees will have direct access to key industry players.

    What Topics Will Be Covered?

    The Mortgage Vision 2026 programme includes a variety of topics that are essential for buy-to-let investors. Key sessions will cover:

    • Market insights into specialist lending and buy-to-let opportunities
    • Technology’s impact on improving business performance
    • Protection and wellbeing in the mortgage industry

    These discussions are designed to help advisers and investors navigate the complexities of the mortgage market, making it a valuable opportunity for those looking to stay ahead.

    What This Means for Mortgage Advisers and Investors

    Mortgage Vision 2026 is set to be a significant event for mortgage advisers and buy-to-let investors. With the mortgage market becoming increasingly complex, the insights gained from this roadshow can help participants identify new growth opportunities and improve operational efficiency. The event aims to equip advisers with the knowledge needed to guide their clients effectively, particularly in the buy-to-let sector, where understanding market trends and financing options is essential.

    Frequently Asked Questions

    When and where will the Mortgage Vision 2026 events take place?

    The events will occur across 12 locations, starting on 8 September 2026 in Elstree and concluding on 14 October 2026 in Gloucester.

    How can I register for Mortgage Vision 2026?

    Registration is complimentary for mortgage advisers, but places are limited and expected to fill quickly. Interested participants should sign up as soon as possible.

  • House Prices Surge: Gap with Flats Widest in 30 Years

    House Prices Surge: Gap with Flats Widest in 30 Years

    The disparity between house and flat prices in the UK has reached its highest level in three decades, with significant implications for buyers and investors. Insight from Zoopla reveals that while the average house price has surged significantly since 2016, flats have seen only a modest increase. This widening gap is particularly pronounced outside London, where houses are now much more expensive than flats.

    TL;DR: The average house in the UK costs significantly more than a flat; this price gap affects first-time buyers and investors alike, particularly in regions like the West Midlands.

    What is the Current Price Gap Between Houses and Flats?

    The average price of a flat in the UK stands at a certain figure, while the typical house is valued at a higher amount. This represents a stark contrast compared to a decade ago when houses were less expensive than flats. The current ratio has expanded significantly, especially outside of London, where houses are now much more costly than flats. The West Midlands has recorded the most significant gap, with houses costing considerably more than flats.

    Why Are House Prices Rising Faster Than Flat Prices?

    Several factors contribute to the differing price trajectories of houses and flats. The average house price has increased substantially due to high demand and limited supply, particularly in desirable areas. In contrast, flats have not experienced the same level of demand, partly due to the prevalence of leasehold arrangements. Zoopla’s analysis indicates that a large proportion of flats for sale in England are leasehold, which often comes with additional costs such as ground rent and service charges, discouraging potential buyers.

    What This Means for First-Time Buyers

    For first-time buyers, the widening gap between house and flat prices presents a dilemma. Many first-time buyers outside London are seeking three-bedroom houses, while a significant number of London first-time buyers prefer flats. The average time to sell a flat varies significantly; in Scotland, flats sell relatively quickly, while in England and Wales (excluding London), the average is longer, and in London, it takes even more time. This complexity in the flat-buying process may deter buyers, making houses a more attractive option despite their higher price.

    What Should Investors Watch For?

    Investors should pay attention to the implications of leasehold properties. The average leasehold running costs can vary significantly, which is a critical factor for lenders. If these costs exceed a certain threshold, it may complicate mortgage approvals, making it essential for investors to consider the financial implications of purchasing flats. Additionally, the stability of flat prices in Scotland, where the long leasehold system does not apply, suggests that regional differences will continue to play a significant role in property investment strategies.

    Frequently Asked Questions

    Why are flats less popular among first-time buyers?

    Flats are often less popular due to the complexities associated with leasehold ownership, including ongoing costs like ground rent and service charges, which can deter potential buyers.

    What impact do leasehold costs have on mortgage approvals?

    High leasehold costs can make it more challenging to secure a mortgage, as lenders may scrutinise properties where costs exceed a certain percentage of their value, complicating the buying process.

  • Why Human Advisors are Essential in the Mortgage Market

    Why Human Advisors are Essential in the Mortgage Market

    The mortgage market in the UK is heavily reliant on human expertise, with nearly 90% of mortgages arranged through intermediaries. This trend highlights the importance of qualified, regulated, and empathetic advice in achieving better outcomes for borrowers. Understanding the complexities of mortgages goes beyond simply securing a competitive interest rate; it involves navigating affordability, deposit options, and future life changes.

    TL;DR: Almost 90% of UK mortgages are arranged by intermediaries, underscoring the value of human advice; this impacts first-time buyers and self-employed individuals who may overlook critical financial nuances.

    Why Are Most Mortgages Arranged by Intermediaries?

    The statistic that nearly 90% of mortgages are arranged by intermediaries is not coincidental. It reflects a broader recognition that human advisors bring essential skills to the table. These professionals are not just facilitators; they provide invaluable insights into the mortgage process, ensuring that borrowers understand the full scope of their options. For instance, a first-time buyer may focus solely on interest rates, neglecting to consider important factors such as their overall affordability and the implications of different deposit amounts.

    What Challenges Do First-Time Buyers Face?

    First-time buyers often enter the mortgage market with a limited understanding of the complexities involved. They may assume that securing a low interest rate is their primary concern, but the reality is much more nuanced. Factors such as family support arrangements, potential future life changes, and the length of the mortgage term can significantly impact their financial health. An intermediary can help them navigate these challenges, ensuring they make informed decisions that align with their long-term goals.

    How Do Self-Employed Borrowers Navigate the Mortgage Market?

    Self-employed individuals face unique hurdles when applying for mortgages. Different lenders have varying criteria for assessing income, which can lead to confusion and frustration. Without expert guidance, a self-employed borrower may not realize that their income could be viewed differently by different lenders. This inconsistency can affect their borrowing capacity and the types of mortgage products available to them. Intermediaries play a critical role in helping these borrowers understand their options and find lenders who will assess their income in a way that reflects their true financial situation.

    What This Means for Borrowers and Brokers

    For borrowers, the reliance on human advisors in the mortgage market means that having access to knowledgeable intermediaries can lead to better financial outcomes. They can receive tailored advice that considers their unique circumstances, which is particularly beneficial for first-time buyers and self-employed individuals. For brokers, this trend underscores the importance of maintaining high standards of service and expertise. As the market continues to evolve, brokers who can provide empathetic and informed guidance will be invaluable to their clients.

    Frequently Asked Questions

    Why is human advice important in the mortgage market?

    Human advice is important because it provides borrowers with tailored insights into their financial situations, helping them navigate complexities like affordability and lender criteria.

    How can first-time buyers benefit from using intermediaries?

    First-time buyers can benefit by receiving guidance on various factors beyond interest rates, such as deposit options and future financial planning, ensuring informed decision-making.

  • Mortgage Mum Partners with HomeOwners Alliance in Mortgage Market

    Mortgage Mum Partners with HomeOwners Alliance in Mortgage Market

    Mortgage Mum, founded by Sarah Tucker, has partnered with HomeOwners Alliance (HOA) to enhance its mortgage commentary and analysis. This collaboration marks a significant shift in the mortgage market, as Tucker assumes the role of HOA’s primary voice on mortgages, leveraging her expertise gained from media appearances on platforms like ITV’s This Morning.

    TL;DR: Sarah Tucker, a prominent mortgage expert, is now the main voice for HomeOwners Alliance on mortgage issues; this partnership aims to provide clearer insights for borrowers and investors.

    Who is Sarah Tucker?

    Sarah Tucker has established herself as a dynamic figure in the mortgage market, known for her engaging media presence. Her role as a mortgage expert on various television and radio segments has positioned her as a trusted source of information. With this new partnership, her insights will be more accessible to homeowners and potential buyers, helping them navigate the complexities of mortgage options.

    What does this mean for the mortgage market?

    The collaboration between Mortgage Mum and HOA is expected to influence the mortgage market by providing clearer, more informed commentary on mortgage trends and policies. As Tucker leads HOA’s mortgage-related discussions, borrowers can anticipate more comprehensive analysis and guidance on navigating their mortgage choices. This could be particularly beneficial for first-time buyers and those looking to remortgage, as they will have access to expert insights that can aid in decision-making.

    What this means for borrowers and investors

    For borrowers, this partnership signifies a potential increase in quality information regarding mortgage options, rates, and market conditions. Investors in the property market may also benefit from enhanced analysis that can inform their strategies, particularly in a fluctuating economic environment. As the mortgage market evolves, staying informed through trusted voices like Tucker will be essential for making sound financial decisions.

    Frequently asked questions

    How will this partnership affect mortgage advice?

    The partnership is expected to provide more comprehensive and accessible mortgage advice, benefiting both homeowners and potential buyers.

    Who should pay attention to this collaboration?

    Borrowers, investors, and brokers should monitor this collaboration for insights that could impact their mortgage decisions and strategies.

  • Mortgage Mum Partners with HomeOwners Alliance on Mortgage Market

    Mortgage Mum Partners with HomeOwners Alliance on Mortgage Market

    Mortgage Mum has announced a significant partnership with HomeOwners Alliance (HOA), appointing founder Sarah Tucker as the organisation’s primary spokesperson on mortgage issues. This collaboration aims to enhance the public’s understanding of the mortgage market, leveraging Tucker’s established media presence and expertise.

    TL;DR: Sarah Tucker, founder of Mortgage Mum, becomes the main voice on mortgages for HomeOwners Alliance; this partnership aims to provide clearer insights into the mortgage market for borrowers and investors.

    Who is Sarah Tucker?

    Sarah Tucker has made a name for herself in the mortgage sector, frequently appearing as an expert on popular media platforms, including ITV’s This Morning. Her dynamic approach and engaging style have positioned her as a trusted voice in the property and mortgage market, making her an ideal choice for HOA to lead their mortgage-related commentary.

    What does this partnership mean for the mortgage market?

    This collaboration is expected to enhance the quality of mortgage-related information available to the public. With Tucker at the helm, HOA aims to provide expert analysis and guidance, which could benefit borrowers, landlords, and investors navigating the complexities of the mortgage market. The partnership signifies a commitment to improving transparency and understanding in the mortgage market.

    What this means for borrowers and investors

    For borrowers, this partnership could lead to more accessible and comprehensible mortgage advice, helping them make informed decisions. Investors and landlords may also find value in the expert insights provided by Tucker, as they navigate current market conditions and seek optimal financing solutions. As the mortgage market evolves, staying informed will be important for all stakeholders.

    Frequently asked questions

    How will this partnership impact mortgage advice?

    The partnership aims to provide clearer and more accessible mortgage insights, benefiting borrowers and investors alike.

    Who benefits most from Sarah Tucker’s expertise?

    Both borrowers seeking guidance and investors looking for strategic insights into the mortgage market will benefit from Tucker’s expertise.