Tag: young adults

  • Young Adults Use Credit to Cover Mortgage Costs

    Young Adults Use Credit to Cover Mortgage Costs

    Recent findings reveal that nearly a third of 18-40-year-olds are using credit to manage their rent or mortgage payments. This trend highlights the increasing financial pressures faced by young adults in the UK housing market, raising concerns about their long-term financial health.

    TL;DR: 70% of young adults rely on credit for housing expenses; this trend creates barriers to future borrowing and financial stability.

    Why Are Young Adults Turning to Credit?

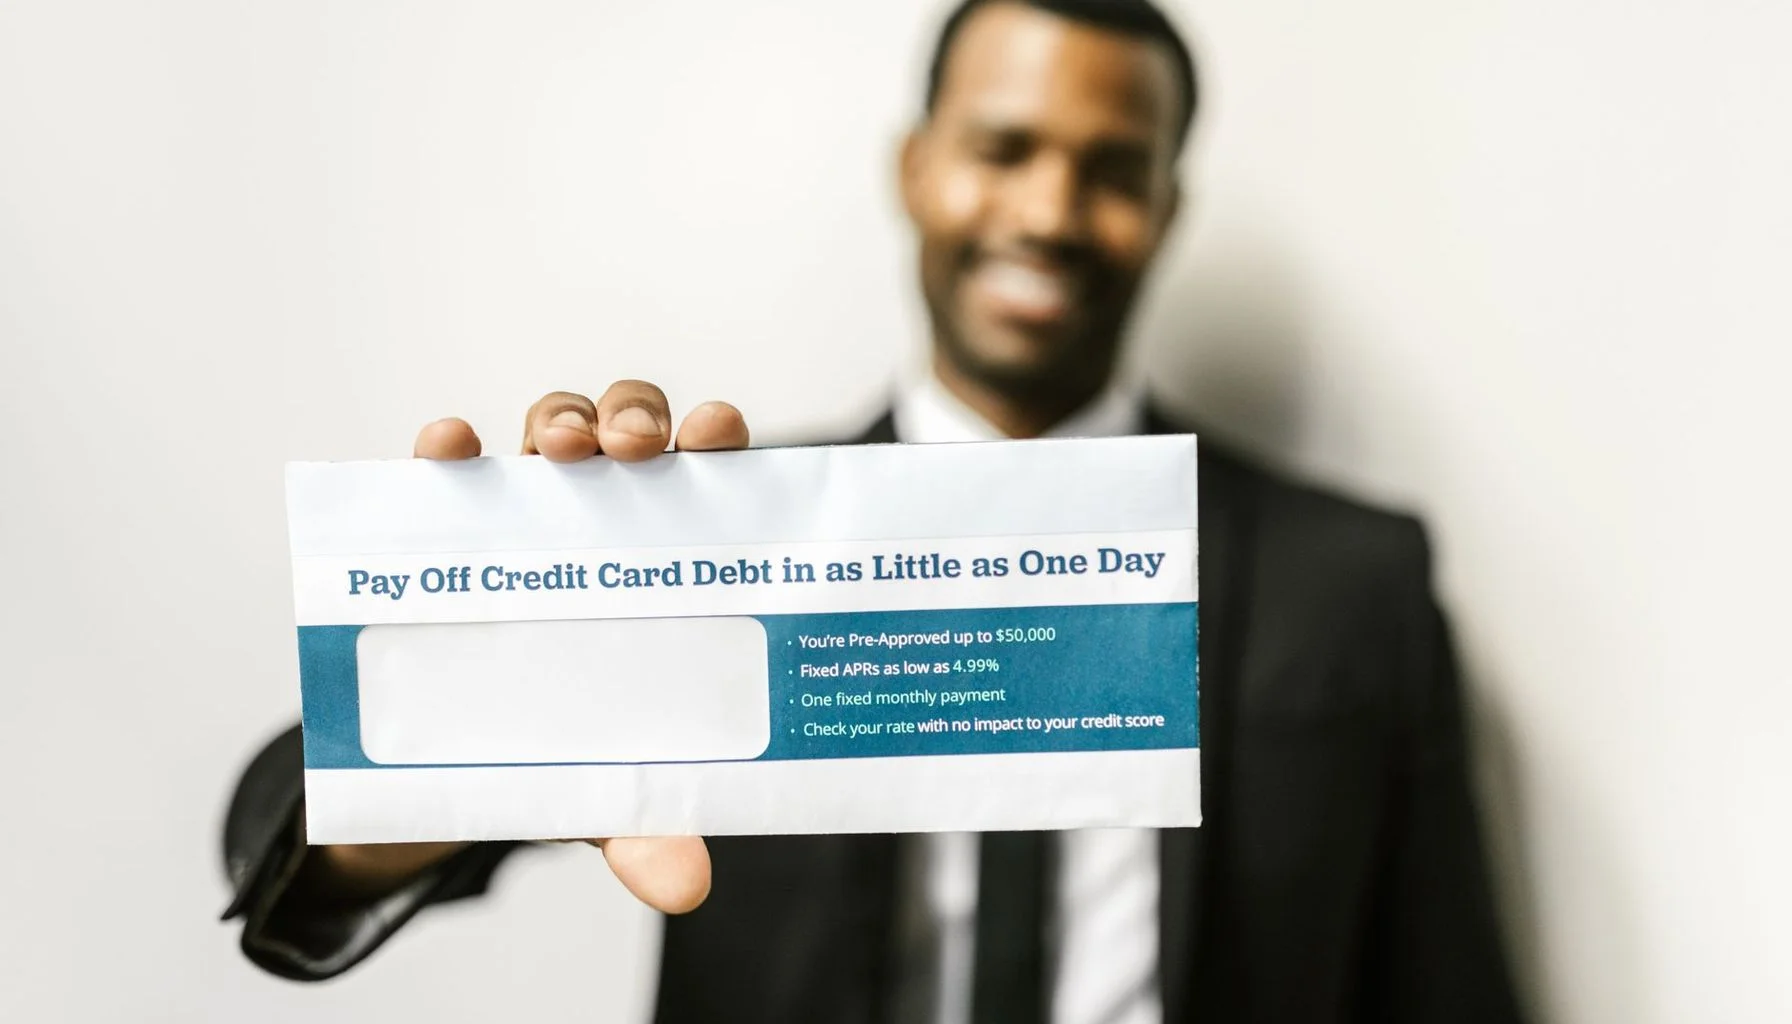
    A significant 70% of young adults have resorted to various forms of credit to cover their housing costs. Among these, 26% have borrowed from family and friends, while 24% have utilised buy now, pay later (BNPL) schemes. Additionally, 21% have relied on bank overdrafts. This reliance on credit indicates a growing trend of ‘survival borrowing’, which can lead to a cycle of debt and financial instability.

    What Impact Does This Have on Mortgage Borrowers?

    The increasing dependence on credit for essential housing expenses poses serious implications for young borrowers. Many are finding themselves in a ‘catch-22’ situation, where their existing credit usage limits their ability to secure further loans or mortgages. This is compounded by the fact that 54% of respondents did not fully understand how their credit history could affect their rental or mortgage applications. The lack of financial education in this area is evident, with 27% of young adults wishing they had learned more about building and maintaining a good credit history before entering the housing market.

    What This Means for Landlords and Investors

    For landlords, the reliance of tenants on credit for housing costs may indicate potential instability in rental payments. As young adults struggle with financial pressures, landlords may face increased risks of late payments or defaults. Investors should consider these trends when assessing the rental market and potential tenant profiles, as the financial health of young adults directly impacts the viability of rental properties.

    Frequently asked questions

    How can young adults improve their credit history?

    Young adults can improve their credit history by making timely payments on loans and credit cards, reducing existing debt, and ensuring they are registered on the electoral roll.

    What should landlords consider when renting to young adults?

    Landlords should assess the financial stability of potential tenants, understanding that many young adults may rely on credit, which could impact their ability to pay rent consistently.
  • AI Adoption in the UK Mortgage Market: A New Trend

    AI Adoption in the UK Mortgage Market: A New Trend

    Young adults are increasingly relying on artificial intelligence (AI) for mortgage advice, marking a significant shift in the UK mortgage market. According to Lloyds Banking Group, a notable portion of individuals aged 35 to 44 have turned to AI for guidance on mortgages, highlighting a growing trend among younger generations to seek tech-driven solutions for financial management.

    TL;DR: A significant portion of 35 to 44-year-olds use AI for mortgage advice; this trend signifies a shift in how young adults approach financial management.

    Why Are Young Adults Turning to AI for Mortgage Advice?

    With the rise of digital tools, many young adults are finding AI to be a convenient source for managing their finances. Among 18 to 24-year-olds, a large percentage have utilized AI for personal finance, showcasing their enthusiasm for technology in financial decision-making. This demographic is also more likely to feel confident about their finances when using digital tools, with a notable portion expressing such confidence.

    How Does AI Impact the Mortgage Market?

    AI’s role in personal finance extends beyond mortgage advice. Among users, many aged 25 to 34 employ AI for budgeting and planning, indicating its effectiveness in helping individuals manage their financial health. This suggests that AI not only aids in securing mortgages but also enhances overall financial literacy and confidence, particularly among younger borrowers.

    What This Means for Borrowers and Brokers

    For borrowers, particularly younger ones, the increasing reliance on AI for mortgage advice can lead to more informed decisions and potentially better mortgage terms. Brokers should consider integrating AI tools into their services to meet the expectations of tech-savvy clients. As AI continues to gain traction, staying updated with the latest digital solutions will be essential for success in the evolving mortgage market. For those looking to explore options, checking current mortgage rates can be beneficial.

    Frequently asked questions

    How can AI improve my mortgage application process?

    AI can streamline the mortgage application process by providing quick assessments, personalized recommendations, and budgeting tools, making it easier for borrowers to navigate their options.

    Are there risks associated with using AI for mortgage advice?

    While AI can provide valuable insights, it’s important to verify the information and consult with a qualified mortgage advisor to ensure that all aspects of your financial situation are considered.

  • Young Adults Embrace AI in the Mortgage Market

    Young Adults Embrace AI in the Mortgage Market

    Young adults in the UK are increasingly relying on artificial intelligence (AI) for mortgage advice, with significant implications for the mortgage market. According to Lloyds Banking Group, a notable proportion of individuals aged 35 to 44 have sought AI assistance for mortgage-related queries, indicating a shift in how this demographic approaches financial decisions.

    TL;DR: A substantial segment of 35 to 44-year-olds use AI for mortgage advice; this trend highlights a growing reliance on technology among younger borrowers.

    Why Are Young Adults Turning to AI for Mortgage Advice?

    The surge in AI usage among young adults can be attributed to the convenience and accessibility of digital tools. A significant percentage of 18 to 24-year-olds have engaged with AI for personal finance management, showcasing their enthusiasm for technology. This demographic values instant information and tailored advice, making AI an appealing option for navigating the complexities of mortgages.

    How Does This Impact the Mortgage Market?

    The increasing reliance on AI for mortgage advice could reshape the mortgage market by encouraging lenders to enhance their digital offerings. As younger borrowers become more comfortable with technology, they may demand more streamlined processes and personalized services. This shift could lead to increased competition among lenders to provide innovative solutions that cater to tech-savvy clients.

    What This Means for Borrowers and Brokers

    For borrowers, particularly those aged 18 to 44, the rise of AI in mortgage advice presents an opportunity to make informed financial decisions with greater confidence. Among users of digital tools, many feel secure about their finances, compared to older generations. Brokers will need to adapt by integrating AI into their services to meet the expectations of younger clients who prefer tech-driven solutions.

    Frequently asked questions

    How can I use AI for mortgage advice?

    Many online platforms offer AI-driven tools that can help you compare current mortgage rates, assess your eligibility, and provide tailored advice based on your financial situation.

    What should I consider when using AI for financial advice?

    While AI can provide valuable insights, it’s essential to cross-check information with trusted sources and consider consulting a financial advisor for complex decisions.