Tag: Property Investment

  • Over 1.5 Million UK Homes Unmortgageable in Mortgage Market

    Over 1.5 Million UK Homes Unmortgageable in Mortgage Market

    Recent research reveals that over 1.5 million homes in the UK are considered ‘unmortgageable’ by mainstream lenders, highlighting a significant challenge in the mortgage market. This situation affects a notable portion of the housing stock, as approximately 6% of the UK’s 28 million residential properties may struggle to secure traditional mortgage finance.

    TL;DR: More than 1.5 million homes in the UK are classified as ‘unmortgageable’ by high street lenders due to various factors; this impacts borrowers, landlords, and investors seeking financing options.

    Why Are Homes Deemed Unmortgageable?

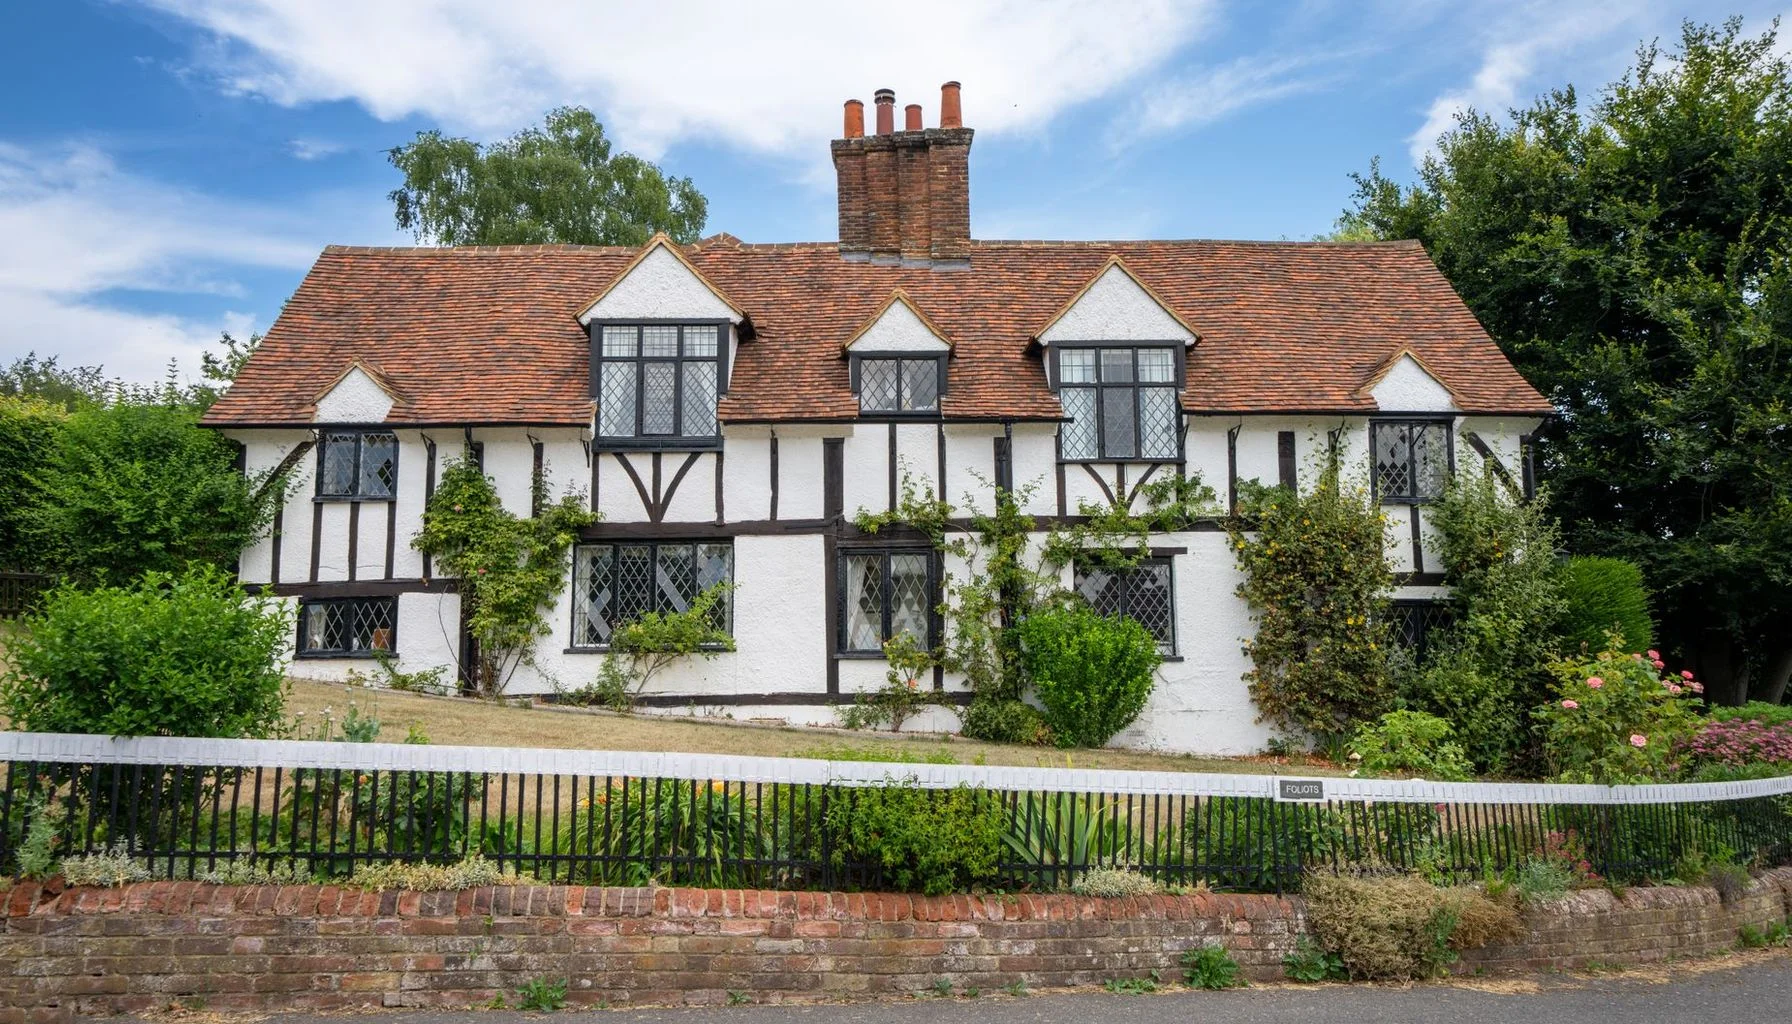
    Properties can be classified as unmortgageable for several reasons, including construction type, lease length, and overall condition. Common examples include thatched cottages, high-rise flats, and homes situated near commercial premises. Additionally, properties lacking essential amenities, such as functioning kitchens or bathrooms, may also face rejection from lenders. These criteria create significant barriers for potential buyers looking to secure mortgage finance.

    Who Is Affected by This Trend?

    This classification impacts a wide range of stakeholders in the property market. First-time buyers and investors may find themselves drawn to these properties due to their lower purchase prices or potential for renovation. In fact, 44% of those who considered buying an unmortgageable property believed it offered better value for money than traditional options. For buy-to-let investors, the prospect of rental income remains a significant incentive, with 35% citing it as their primary motivation.

    What Should Buyers and Investors Watch For?

    Potential buyers should be aware that nearly one in five respondents reported having a mortgage application rejected due to their property’s classification. Furthermore, 32% indicated they had access to a limited pool of lenders willing to consider their applications. This situation suggests that buyers need to conduct thorough research and possibly seek alternative financing solutions, such as specialist lenders who may cater to unmortgageable properties.

    What This Means for Landlords and Investors in the Mortgage Market

    Landlords and property investors should consider the risks and rewards associated with purchasing unmortgageable properties. While the lower purchase prices can be attractive, the potential challenges in securing financing and the need for renovations could complicate investment strategies. However, 31% of buyers felt that the risk-to-reward ratio was worthwhile, indicating that there are opportunities for those willing to navigate the complexities of this market. For those looking to explore financing options, checking current mortgage rates may provide insight into available products.

    Frequently asked questions

    What types of properties are often deemed unmortgageable?

    Properties such as thatched cottages, high-rise flats, and homes without essential amenities like kitchens or bathrooms are commonly classified as unmortgageable by mainstream lenders.

    How can buyers finance unmortgageable properties?

    Buyers may need to seek alternative financing options, such as specialist lenders who focus on properties that do not meet traditional mortgage criteria, as mainstream lenders may reject their applications.
  • 1.5 Million Homes Impacting the UK Mortgage Market

    1.5 Million Homes Impacting the UK Mortgage Market

    Recent research has revealed that over 1.5 million homes in the UK are considered ‘unmortgageable’ by mainstream lenders. This significant figure highlights a growing concern in the mortgage market, as many properties fail to meet traditional lending criteria, impacting potential buyers and investors alike.

    TL;DR: More than 1.5 million UK homes are deemed ‘unmortgageable’ due to factors like construction type and condition; this affects borrowers seeking financing options.

    What Makes a Property Unmortgageable?

    According to the findings, approximately 6% of the UK’s 28 million residential properties may struggle to secure mainstream mortgage finance. Factors contributing to this classification include:

    • Construction type, such as thatched cottages and high-rise flats
    • Lease length
    • Condition of the property, including those lacking functioning kitchens or bathrooms
    • Proximity to commercial premises

    These criteria can severely limit the options available for buyers looking to finance their property purchases.

    Why Are Buyers Interested in Unmortgageable Properties?

    Despite the challenges, many buyers are drawn to unmortgageable properties for various reasons. Among those who have considered purchasing such properties:

    • 44% believe these homes offer better value for money compared to traditional properties.
    • 31% are motivated by the chance to renovate or restore the property.
    • 28% aim to add value before selling for a profit.
    • 31% see a worthwhile risk-to-reward ratio, despite acknowledging the process may be difficult.
    • 21% feel the potential rewards outweigh the risks.
    • 19% are willing to take on properties that others might avoid.

    This interest suggests a segment of the market is willing to embrace the challenges associated with these properties for the potential of greater returns.

    What This Means for the Mortgage Market

    The implications for buyers and investors are significant. With over a quarter (28%) of respondents citing lower purchase prices as the main attraction, this can be particularly appealing for first-time buyers and buy-to-let investors. For those purchasing as their primary residence, this figure rises to 32%. Additionally, 35% of buy-to-let investors are motivated by the prospect of rental income from such properties.

    However, potential buyers should be aware that 21% of respondents reported having their mortgage applications rejected, and 32% indicated limited access to lenders willing to consider their applications. This highlights the importance of understanding the mortgage market and exploring alternative financing options when considering unmortgageable properties.

    Frequently Asked Questions

    What should I consider when buying an unmortgageable property?

    When considering an unmortgageable property, assess its condition, potential renovation costs, and the availability of financing options. Understanding the risks involved is important.

    How can I finance an unmortgageable property?

    Alternative financing options may include specialist lenders who cater to unmortgageable properties or considering cash purchases if feasible. Researching these options is essential.

  • Semi-Commercial Mortgage Lending to Exceed £1 Billion

    Semi-Commercial Mortgage Lending to Exceed £1 Billion

    The semi-commercial mortgage sector is poised for significant growth, with lending expected to surpass £1 billion by the end of 2026. This surge is driven by an increase in transaction volumes and average loan sizes, indicating a robust market for landlords and investors in mixed-use properties.

    TL;DR: Semi-commercial mortgage lending is projected to exceed £1 billion by 2026, with a 20% increase in lending from the previous year; this trend benefits landlords and investors seeking mixed-use properties.

    What is Driving the Growth in Semi-Commercial Mortgages?

    In the second quarter of 2026, semi-commercial lending reached £242 million, marking a 20% increase from £201 million in the same period last year. This growth reflects a broader trend in the semi-commercial mortgage market, which encompasses properties that combine residential and commercial uses. The number of transactions also rose by 13%, from approximately 415 in Q2 2025 to 470 in Q2 2026, suggesting a healthy appetite for these types of loans.

    How Are Average Loan Sizes Changing?

    Average loan sizes have seen a notable increase of about 6% year on year, climbing from £484,000 to £515,000. This rise in loan size has contributed to the overall growth in lending value, indicating that borrowers are taking on larger projects or investing in more valuable properties. This trend is essential for investors looking to finance bigger developments in the mixed-use sector.

    What This Means for Landlords and Investors

    For landlords and investors, the expanding semi-commercial mortgage market presents opportunities for diversification and growth. With an increase in active lenders from 25 to 28 over the past year and a nearly 20% rise in dedicated semi-commercial mortgage products to 94, borrowers have more options available. The average loan-to-value ratio has also increased from 64% to 67%, allowing investors to use their assets more effectively.

    Challenger banks and specialist lenders are stepping in where mainstream banks have scaled back, particularly after the 2008 financial crisis. This shift has created a more competitive environment, benefiting borrowers with more tailored products and potentially better rates. As the market continues to grow, stakeholders should keep an eye on lending trends and product offerings to capitalize on emerging opportunities.

    What Are Current Interest Rates Like?

    Average headline fixed rates have eased slightly to around 6.70%, down from 6.85% in the first quarter of 2026. Challenger and specialist lenders are offering rates that range from approximately 6.0% to 9.0%, depending on the complexity of the asset and the transaction. This slight reduction in rates may encourage more borrowers to enter the market, further driving up lending volumes.

    Frequently Asked Questions

    What types of properties qualify for semi-commercial mortgages?

    Semi-commercial mortgages are designed for properties that have both residential and commercial elements, such as a shop with flats above or a mixed-use development. These properties must be secured against a single title.

    How can I find the best rates for semi-commercial mortgages?

    To find the best rates, borrowers should compare offers from various lenders, including challenger banks and specialist lenders. It’s also beneficial to consult with a mortgage broker who specializes in commercial mortgages to access a wider range of products and rates.

  • RAW Capital Partners Launches New Bridging Loan Service

    RAW Capital Partners Launches New Bridging Loan Service

    RAW Capital Partners has expanded its offerings by introducing bridging loans, a move that enhances its specialist lending portfolio. This development is significant for landlords and property investors seeking swift financing options, particularly in the current dynamic property market.

    TL;DR: RAW Capital Partners now offers bridging loans ranging from £100,000 to £4 million, targeting landlords and investors needing quick access to funds; loans are secured against UK residential property with a maximum loan-to-value ratio of 60%.

    What Are the Key Features of RAW’s Bridging Loans?

    The new bridging loans from RAW Capital Partners are unregulated, first-charge loans secured against UK residential properties. Borrowers can access loans starting from £100,000 up to £4 million, with terms ranging from three to 18 months. The maximum loan-to-value (LTV) ratio is set at 60%, and interest rates are tiered based on the LTV.

    Who Can Benefit from These Bridging Loans?

    This new offering is particularly beneficial for foreign nationals, UK expatriates, and Channel Islanders who have previously invested in UK buy-to-let properties. Following an expansion of lending criteria in December 2025, UK residents can now also apply for these loans, broadening the potential customer base significantly.

    What This Means for Landlords and Investors

    The introduction of bridging loans by RAW Capital Partners provides landlords and property investors with a fast and reliable financing option. With the RAW Mortgage Fund managing over £220 million in assets, the lender is well-positioned to deliver quick decisions and funding, which is important for those looking to seize investment opportunities in a competitive market.

    Frequently asked questions

    What is a bridging loan?

    A bridging loan is a short-term financing option that helps borrowers bridge the gap between purchasing a new property and selling their existing one or securing long-term financing.

    How do I apply for a bridging loan with RAW Capital Partners?

    To apply for a bridging loan, contact RAW Capital Partners directly or work through a mortgage broker who can assist you with the application process.

  • RAW Capital Partners Launches Bridging Loans in UK

    RAW Capital Partners Launches Bridging Loans in UK

    RAW Capital Partners, a specialist lender based in Guernsey, has expanded its product offerings by introducing bridging loans secured against UK residential properties. This move is significant as it allows a broader range of borrowers, including foreign nationals and UK residents, to access quick financing solutions for property investments.

    TL;DR: RAW Capital Partners now offers bridging loans from £100,000 to £4 million for terms of three to 18 months; this change benefits landlords and investors seeking fast funding options.

    What are the Key Features of RAW’s Bridging Loans?

    The newly launched bridging loans are unregulated and come with first-charge security against residential properties in the UK. Borrowers can access loans ranging from £100,000 to £4 million, with a maximum loan-to-value (LTV) ratio of 60%. The interest rates are tiered based on the LTV, providing flexibility for different borrowing scenarios. These loans are funded through the RAW Mortgage Fund, which boasts over £220 million in assets under management.

    Who Can Benefit from These Bridging Loans?

    The introduction of bridging loans by RAW Capital Partners is particularly beneficial for landlords and property investors looking for quick financing solutions. With terms of three to 18 months, these loans can facilitate timely property acquisitions or renovations, enabling investors to act swiftly in a competitive market. The recent expansion of lending criteria to include UK residents further broadens the potential borrower base.

    What This Means for Borrowers and Brokers

    This development is a positive sign for brokers and borrowers alike, as it enhances the options available in the bridging loan market. Speed and certainty are highlighted as key qualities of RAW’s offering, which may help streamline the property investment process. As the demand for bridging finance continues to grow, brokers should keep an eye on how this new product can meet their clients’ needs.

    Frequently asked questions

    What is a bridging loan?

    A bridging loan is a short-term financing option used to bridge the gap between the purchase of a new property and the sale of an existing one.

    How can I apply for a bridging loan with RAW Capital Partners?

    Interested borrowers can contact RAW Capital Partners directly or work with a mortgage broker to explore their bridging loan options.

  • UK Mortgage Market Updates: Key Changes and Impacts

    UK Mortgage Market Updates: Key Changes and Impacts

    The UK mortgage market is witnessing significant developments this week, with key announcements affecting borrowers and lenders alike. Prime Minister Andy Burnham has ruled out changes to stamp duty in the upcoming budget, while Aldermore has increased its maximum loan-to-value (LTV) ratio to 98%, a move that could reshape lending dynamics for buyers.

    TL;DR: Aldermore has raised its maximum LTV to 98%, impacting employed borrowers seeking higher loans; meanwhile, no changes to stamp duty are expected, affecting market stability.

    What does Aldermore’s LTV increase mean for borrowers?

    Aldermore’s decision to raise its maximum LTV to 98% is a notable shift in the mortgage market, particularly for employed borrowers. This increase allows buyers to secure larger loans with a smaller deposit, which can be a game-changer for first-time buyers or those with limited savings. The new five-tier product structure aims to cater to customers with complex financial situations, potentially broadening access to homeownership.

    How will the stamp duty announcement affect the market?

    With Prime Minister Andy Burnham confirming that there will be no changes to stamp duty in the forthcoming budget, the current tax structure remains intact. This stability may provide reassurance to potential buyers and investors, as they can plan their purchases without the uncertainty of imminent tax reforms. However, the lack of reform may also mean that the market continues to face challenges, particularly in regions where affordability is already strained.

    What are the implications of the recent mortgage rate changes?

    Several lenders, including Halifax, BM Solutions, TSB, and Leeds Building Society, are increasing selected mortgage rates by up to 20 basis points. This adjustment reflects ongoing pressure from rising funding costs, which could lead to higher borrowing costs for consumers. Borrowers should be aware that competitive mortgage deals may become less available as lenders adjust their pricing strategies in response to market conditions.

    What this means for landlords and property investors

    For landlords and property investors, the changes in the mortgage market signal a need for vigilance. The increase in LTV by Aldermore may open doors for more buyers, potentially boosting demand in certain segments of the market. However, the rising mortgage rates could dampen overall buyer enthusiasm, particularly in areas already facing price stagnation or decline. Investors should keep an eye on regional market trends and consider how these developments might impact rental yields and property values.

    Frequently asked questions

    What is the current state of the mortgage market?

    The mortgage market is currently experiencing a mix of stability and change, with Aldermore increasing its maximum LTV to 98% and several lenders raising their mortgage rates. This environment presents both opportunities and challenges for borrowers and investors.

    How can I find the best mortgage rates available?

    To find the best mortgage rates, consider using a mortgage rate comparison tool, which can help you evaluate different lenders and products based on your specific financial situation.

  • Paragon Cuts Buy-to-Let Rates: What Landlords Need to Know

    Paragon Cuts Buy-to-Let Rates: What Landlords Need to Know

    Paragon Bank has announced a reduction on a selection of its five-year fixed-rate buy-to-let mortgages. This adjustment reflects a recent cooling in swap rates and aims to provide landlords with more competitive borrowing options.

    TL;DR: Paragon Bank has reduced rates on five-year buy-to-let mortgages; this change benefits landlords seeking competitive financing options.

    What Changes Have Been Made to Buy-to-Let Rates?

    The updated range from Paragon Bank includes products with various loan-to-value (LTV) ratios. The starting rates for these products now include options for green mortgages, which apply to properties with specific EPC ratings. Additionally, there are options available for Houses in Multiple Occupation (HMOs) and Multi-Unit Blocks (MUBs). Landlords can choose from various fee structures, including nil-fee, percentage-fee, and fixed-fee options, with selected products offering cashback.

    Who Will Benefit from These Rate Cuts?

    This rate reduction primarily benefits landlords looking to finance their buy-to-let investments. With the introduction of competitive rates, landlords can potentially reduce their borrowing costs, making property investment more attractive. Paragon’s tailored proposition also accommodates applications that fall outside standard lending criteria, widening access for a broader range of investors.

    What This Means for Landlords

    Frequently asked questions

    What are the new rates for Paragon’s buy-to-let mortgages?

    The new rates include options for green mortgages on properties with specific EPC ratings, as well as options for HMOs and MUBs.

    How can landlords take advantage of these rate cuts?

    Landlords can benefit by refinancing existing mortgages or securing new loans at lower rates, potentially reducing overall borrowing costs and improving investment returns.

  • UK Mortgage Market Updates: Key Changes This Week

    UK Mortgage Market Updates: Key Changes This Week

    The UK mortgage market is experiencing significant developments this week, impacting borrowers, lenders, and investors alike. Notably, Prime Minister Andy Burnham has confirmed that there will be no changes to stamp duty in the upcoming autumn Budget, while Aldermore has increased its maximum loan-to-value (LTV) ratio to 98%, providing new opportunities for borrowers.

    TL;DR: Aldermore has raised its maximum LTV to 98% for employed borrowers; meanwhile, no changes to stamp duty are expected in the autumn Budget, affecting potential homebuyers and investors.

    What are the latest changes in mortgage lending?

    Aldermore’s recent move to raise its maximum LTV to 98% marks a significant shift in its residential mortgage offerings. This change aims to support employed borrowers, particularly those with complex financial situations, by introducing a five-tier product structure. This enhanced flexibility could make homeownership more accessible for many who have struggled to secure financing under previous LTV limits.

    How will the stamp duty announcement affect the market?

    With Prime Minister Andy Burnham ruling out any changes to stamp duty in the autumn Budget, potential homebuyers can expect stability in this area for the time being. This decision may alleviate some uncertainty in the market, allowing buyers to plan their purchases without the fear of sudden tax increases. However, it also means that the current stamp duty framework will remain in place, which could be a barrier for first-time buyers and those looking to move up the property ladder.

    What does the latest mortgage market data reveal?

    The latest data from Network Consulting indicates a shifting market within the mortgage network sector. While Primis remains the largest mortgage network, it has seen a slight decline in appointed representatives. In contrast, Stonebridge, HL Partnership, and ValidPath have reported net growth in adviser firms. This trend suggests that while some networks are consolidating, others are expanding, reflecting varying levels of confidence and demand in the mortgage market.

    What this means for borrowers and investors

    For borrowers, Aldermore’s increased LTV ratio could open doors to homeownership that were previously closed, especially for those with unique financial needs. However, with Halifax, BM Solutions, TSB, and Leeds Building Society raising selected mortgage rates by up to 20 basis points, borrowers should be cautious. The rising rates, driven by higher funding costs and geopolitical uncertainties, may limit the availability of competitive mortgage deals. Investors should also be aware of these changes, as the slowing annual house price growth of 1.3% and the ongoing decline in London property values could impact investment strategies.

    Frequently asked questions

    What are the implications of the new LTV ratio for borrowers?

    The increase in Aldermore’s maximum LTV to 98% allows employed borrowers, especially those with complex financial situations, to access higher loan amounts with a smaller deposit. This could make it easier for many to enter the housing market.

    How will the lack of stamp duty changes affect homebuyers?

    The decision to maintain the current stamp duty framework provides clarity for homebuyers, allowing them to make informed decisions without the risk of sudden tax increases. However, it also means that the existing challenges related to stamp duty will continue to affect affordability for many buyers.

  • 1.5 Million UK Homes Impacting the Mortgage Market

    1.5 Million UK Homes Impacting the Mortgage Market

    Recent research reveals that over 1.5 million homes in the UK are considered ‘unmortgageable’ by mainstream lenders, significantly impacting the mortgage market. This situation arises from various factors, including construction types, lease lengths, and property conditions, which restrict access to traditional mortgage finance.

    TL;DR: More than 1.5 million UK homes are classified as unfit for standard mortgages; this affects borrowers seeking financing for unique properties.

    What Types of Properties Are Unmortgageable?

    According to the findings, properties that fall outside traditional lending criteria include thatched cottages, high-rise flats, and homes near commercial premises. Additionally, properties lacking essential facilities, such as functioning kitchens or bathrooms, are also deemed unmortgageable. This classification affects around 6% of the UK’s 28 million residential properties, limiting options for potential buyers.

    Why Are Buyers Interested in Unmortgageable Properties?

    Despite the challenges, many buyers are drawn to these properties for various reasons. A significant 44% of respondents believe that such homes offer better value for money compared to traditional properties. Furthermore, 31% are motivated by the potential to renovate or restore these homes, while 28% hope to increase their value before selling them for a profit. This indicates a growing interest in properties that require investment and improvement.

    What This Means for the Mortgage Market

    For borrowers, the classification of properties as unmortgageable presents a significant hurdle. More than one in five respondents reported having their mortgage applications rejected due to the nature of their desired properties. Additionally, 32% of buyers noted that they had access to a limited number of lenders willing to consider their applications. For investors, particularly those in the buy-to-let market, the prospect of lower purchase prices and potential rental income can be appealing, with 35% citing rental income as their primary motivation.

    How Can Buyers Navigate This Challenge?

    Understanding the specific criteria that lenders use to classify properties can help buyers make informed decisions. Engaging with specialist lenders who cater to non-standard properties may provide alternative financing options. Buyers should also consider the renovation costs and potential risks involved in purchasing unmortgageable homes. The willingness to take on such properties can lead to rewarding opportunities, but it requires careful planning and consideration.

    Frequently asked questions

    What should I consider before buying an unmortgageable property?

    Before purchasing an unmortgageable property, assess the renovation costs, potential risks, and your access to financing. Engaging with specialist lenders can provide insights and options tailored to your situation.

    Are there lenders that finance unmortgageable properties?

    Yes, some lenders specialize in financing non-standard properties. It’s essential to research and reach out to these lenders to explore your financing options.

  • Over 1.5 Million UK Homes Impacting the Mortgage Market

    Over 1.5 Million UK Homes Impacting the Mortgage Market

    Recent research indicates that over 1.5 million homes in the UK are classified as ‘unmortgageable’ by mainstream lenders. This situation arises due to various factors including construction types, lease lengths, and property conditions, which fall outside traditional lending criteria. Understanding these challenges is important for buyers and investors looking to navigate the mortgage market.

    TL;DR: More than 1.5 million UK homes are deemed ‘unmortgageable’ by high street lenders; this affects buyers and investors seeking financing for unique properties.

    What Makes a Property Unmortgageable?

    Properties can be classified as unmortgageable for several reasons. High street lenders often reject homes that are unconventional in construction, such as thatched cottages or high-rise flats. Additionally, properties located near commercial premises or those lacking essential amenities like functioning kitchens or bathrooms also face challenges securing financing. The study highlights that around 6% of the UK’s 28 million residential properties could struggle to obtain mainstream mortgage finance due to these criteria.

    Why Are Buyers Interested in Unmortgageable Properties?

    Despite the challenges, many buyers are drawn to unmortgageable properties for various reasons. Approximately 44% of respondents who considered such homes believed they offered better value for money compared to traditional properties. Renovation opportunities are also appealing, with 31% motivated by the chance to restore a property, while 28% aim to add value before selling it for profit. This interest reflects a growing trend among buyers willing to undertake projects that others might avoid.

    What This Means for the Mortgage Market

    For landlords and investors, the mortgage market is shifting. The potential for lower purchase prices is a significant draw, particularly for buy-to-let investors, 35% of whom cite rental income as their primary incentive. However, the challenges of obtaining financing remain evident, with 21% of respondents reporting previous mortgage application rejections and 32% facing a limited pool of lenders willing to consider their applications. This situation necessitates a strategic approach for investors looking to capitalize on the opportunities presented by unmortgageable properties.

    How Can Buyers Navigate the Mortgage Market?

    Understanding the intricacies of the mortgage market is essential for prospective buyers of unmortgageable properties. Engaging with specialist lenders who are more open to unconventional properties can be beneficial. Additionally, buyers should be prepared for a potentially lengthy and challenging process, as indicated by the 31% who acknowledge the risk-to-reward ratio involved. Being informed about current mortgage rates and exploring options through mortgage rate comparison tools can also aid in making well-rounded decisions.

    Frequently asked questions

    What types of properties are typically unmortgageable?

    Common examples include thatched cottages, high-rise flats, and homes lacking essential amenities like kitchens or bathrooms. Properties near commercial premises may also face challenges.

    How can buyers secure financing for unmortgageable properties?

    Buyers should consider engaging with specialist lenders who are more willing to finance unconventional properties. Researching current mortgage rates and comparing options can also help in securing the best deal.