Tag: investing

  • UK Housing Market Stalls: Impact on Mortgages Explained

    UK Housing Market Stalls: Impact on Mortgages Explained

    The UK housing market is experiencing a slowdown, with house prices remaining unchanged in September, according to the latest Lloyds house price index. This stagnation follows a 0.3% decline in August, indicating a loss of momentum that could impact borrowers and investors alike.

    TL;DR: House prices across the UK have stalled, with annual growth remaining flat; this trend is affecting buyer confidence and could lead to cautious mortgage decisions.

    What Are the Key Trends in House Prices?

    The Lloyds index highlights significant regional variations in house price performance. Northern Ireland leads with a 7.4% year-on-year increase, reaching an average price of £231,287. Scotland also saw a rise of 3.4%, with average prices at £223,330, while Wales experienced a modest growth of 1.2% to £231,287.

    In England, the North East recorded the strongest growth at 2.4%, with average prices now at £184,546. The North West followed closely with a 1.9% increase, bringing average prices to £248,932. The West Midlands was the only other English region to show positive growth, albeit at a modest 0.8% to £260,892.

    Conversely, the South East saw a decline of 2.1%, with average prices falling to £380,829. The South West also experienced a decrease of 1.4%, averaging £299,572, while Greater London faced the largest drop, with prices down 2.2% to £531,548.

    Why Are Prices Stalling?

    Several factors contribute to the current stagnation in house prices. Economic uncertainty, particularly due to geopolitical tensions in the Middle East, has dampened buyer confidence. Additionally, the prospect of higher mortgage rates and the upcoming Budget have led to a more cautious approach among potential buyers.

    Andrew Asaam, mortgages director at Lloyds, noted that despite the subdued market, property prices have shown resilience during this period of elevated rates. However, he emphasized that confidence remains a critical driver of housing market activity, which will influence demand in the months ahead.

    What This Means for Mortgage Borrowers and Investors

    For borrowers, particularly those approaching the end of fixed-rate mortgages, this market environment presents challenges. Many will face significant payment shocks when transitioning from historically low fixed rates of around 1%. This could lead to increased financial strain for those remortgaging, especially if they are unable to secure competitive rates.

    Landlords and property investors should also take note of the shifting dynamics. While some regions are still experiencing growth, the overall trend suggests a more cautious investment climate. Investors may need to reassess their strategies and consider the implications of rising costs and changing buyer sentiment.

    Frequently Asked Questions

    How can I prepare for potential mortgage payment increases?

    Borrowers should review their current mortgage agreements and explore options for remortgaging ahead of time. Consulting with a mortgage broker can help identify the best available rates and terms.

    What should investors consider in the current housing market?

    Investors should evaluate the regional performance of properties and consider diversifying their portfolios. Staying informed about economic trends and buyer sentiment will be important for making sound investment decisions.
  • Over 1.5 Million UK Homes Considered Unmortgageable

    Over 1.5 Million UK Homes Considered Unmortgageable

    Recent research from specialist lender Together reveals that over 1.5 million homes in the UK may be deemed “unmortgageable” by mainstream lenders. This situation arises from various factors that fall outside the typical lending criteria of high street banks, significantly impacting potential buyers and investors.

    TL;DR: More than 1.5 million homes in the UK are classified as “unmortgageable” due to issues like short leases and structural concerns; this limits options for buyers and investors seeking properties outside standard criteria.

    What Makes a Home Unmortgageable?

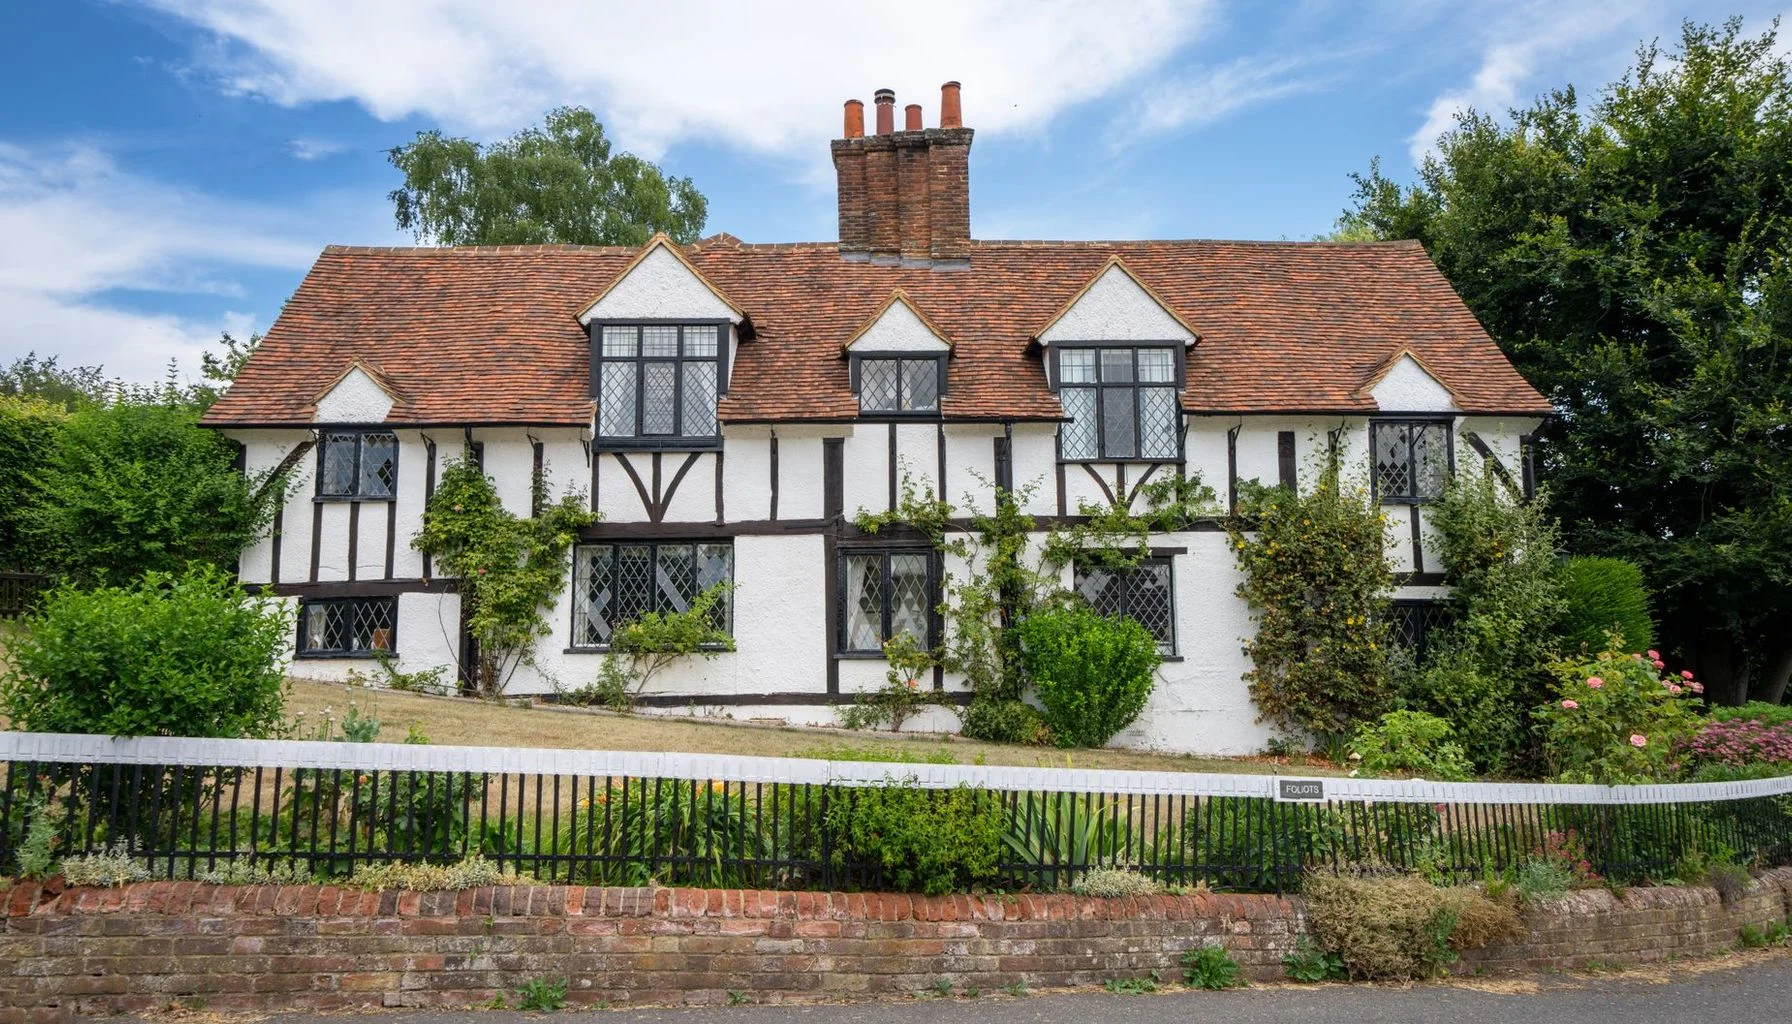
    According to Together’s findings, approximately 6% of the UK’s 28 million residential properties are considered unfit for standard mortgage applications. Key factors contributing to this classification include thatched roofs, short leases, solid-wall construction, high-rise locations, and proximity to commercial premises. Additionally, properties lacking essential amenities like a functioning kitchen or bathroom are also affected.

    Who is Affected by This Classification?

    The implications of these findings extend to various groups, including first-time buyers, landlords, and property investors. Among those who have considered purchasing such properties, 44% believe these homes offer better value compared to conventional options. Furthermore, 31% are interested in renovation projects, while 28% view these properties as opportunities to increase value before resale.

    What This Means for Buyers and Investors

    For potential buyers, the classification of homes as unmortgageable can significantly narrow their choices. Over a quarter of prospective buyers (28%) cited lower purchase prices as a primary incentive for pursuing these properties. However, 21% of buyers have faced mortgage application rejections, and 32% reported limited lender options willing to consider their applications. This trend may create challenges for those looking to enter the property market, particularly in areas with a high concentration of such homes.

    Frequently Asked Questions

    What should I do if my mortgage application is rejected?

    If your mortgage application is rejected, consider seeking advice from a mortgage broker who can help identify lenders that may be more flexible with their criteria.

    Are there alternative financing options for unmortgageable properties?

    Yes, alternative financing options such as bridging loans or specialist lenders may be available for properties that do not meet standard mortgage criteria.

  • 1.5 Million UK Homes Unmortgageable: What It Means

    1.5 Million UK Homes Unmortgageable: What It Means

    Recent research indicates that over 1.5 million homes in the UK are deemed ‘unmortgageable’ by mainstream lenders, impacting potential buyers and investors. This situation arises from properties failing to meet the lending criteria set by high street banks, which could limit the housing options available to many.

    TL;DR: More than 1.5 million UK homes are considered ‘unmortgageable’ due to various factors, affecting buyers and investors seeking alternative properties; 21% of buyers have faced mortgage application rejections.

    What Makes a Home Unmortgageable?

    Properties may be classified as unfinanceable for several reasons, including structural issues like thatched roofs or solid-wall construction, as well as practical concerns such as short leases or the absence of essential amenities like kitchens and bathrooms. Additionally, locations near commercial premises or high-rise buildings can deter lenders from approving mortgages.

    Who Is Affected by This Situation?

    This issue primarily impacts buyers looking for affordable housing options, particularly those interested in renovation projects. Among potential buyers, 44% believe these properties offer better value compared to conventional homes. Furthermore, 35% of buy-to-let investors are drawn to these properties due to their rental income potential, despite the challenges in securing financing.

    What This Means for Buyers and Investors

    For individuals and investors in the property market, the high number of unfinanceable homes could limit choices and complicate the purchasing process. The research indicates that 21% of buyers have already experienced mortgage application rejections, while 32% reported a reduced pool of lenders willing to consider their applications. This highlights the necessity for alternative financing options or specialist lenders who can accommodate these unique properties.

    Frequently Asked Questions

    What should buyers do if their property is unfinanceable?

    Buyers should consider seeking out specialist lenders who are more flexible with their criteria or explore alternative financing options such as renovation loans or bridging finance.

    How can investors benefit from unmortgageable properties?

    Investors may find unmortgageable properties appealing due to lower purchase prices and potential for value increase through renovations, despite the challenges in securing financing.