Tag: buy-to-let

  • 1.5 Million UK Homes Unmortgageable: Impact on Mortgage Market

    1.5 Million UK Homes Unmortgageable: Impact on Mortgage Market

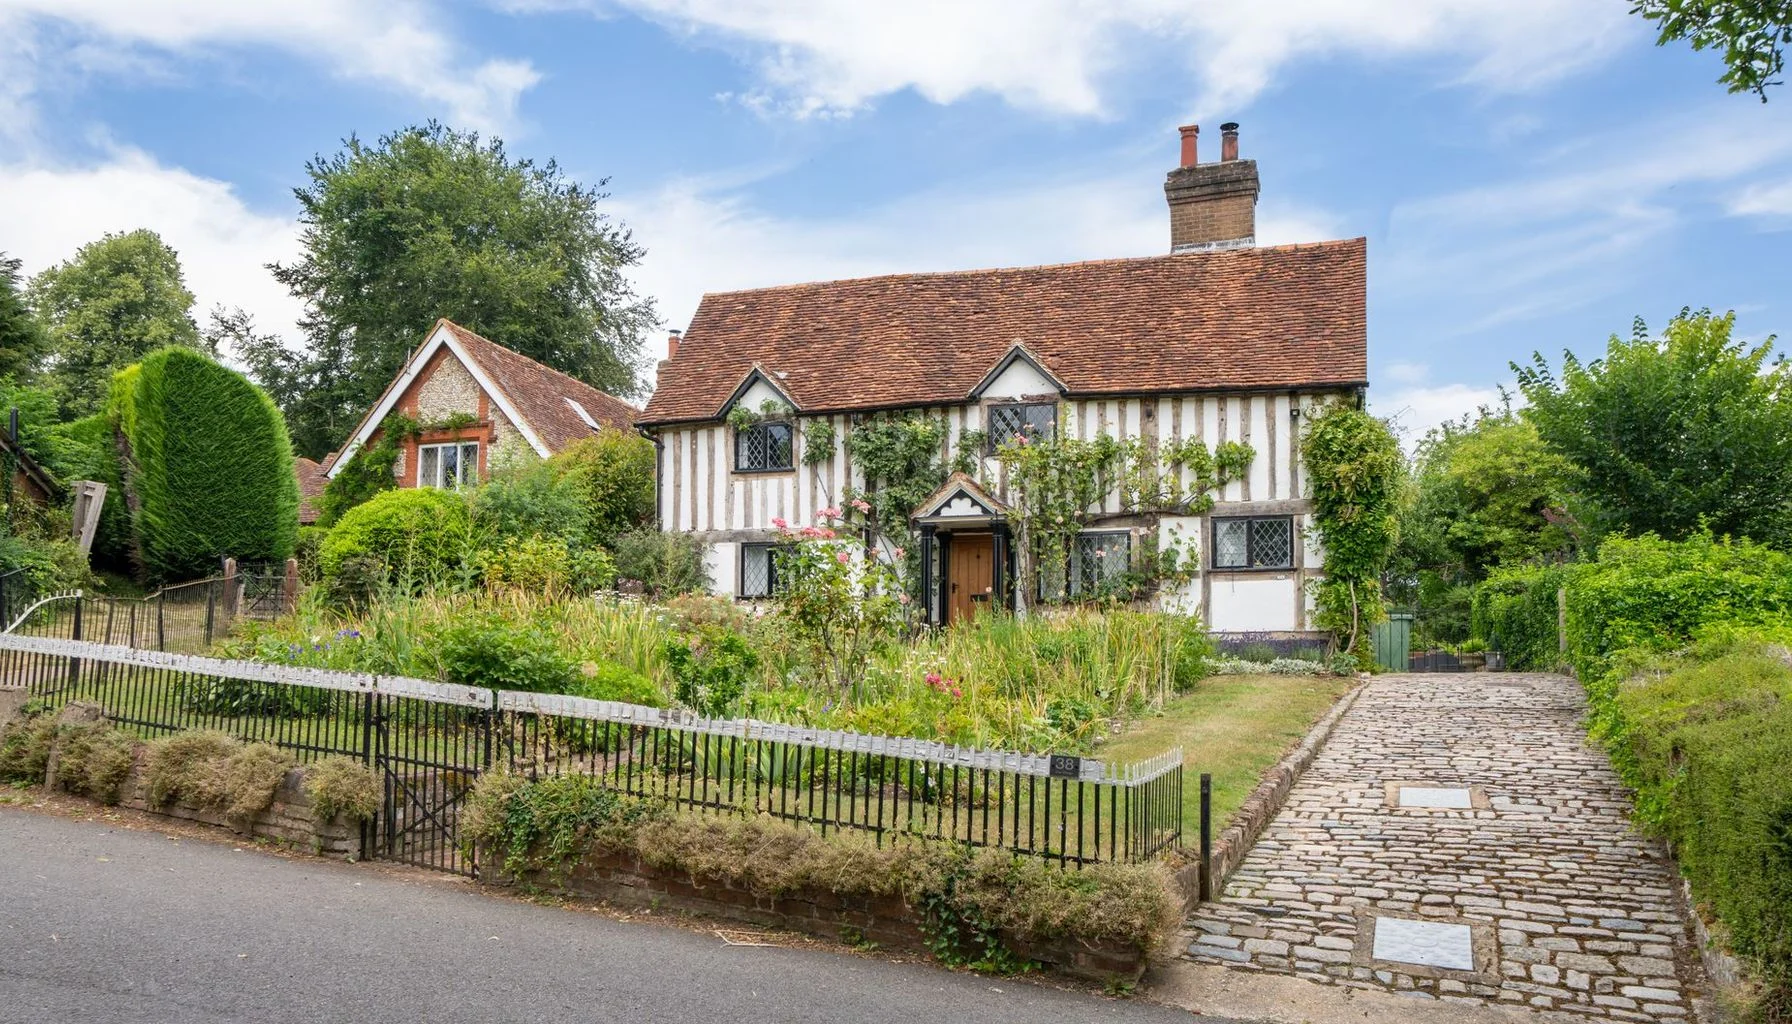
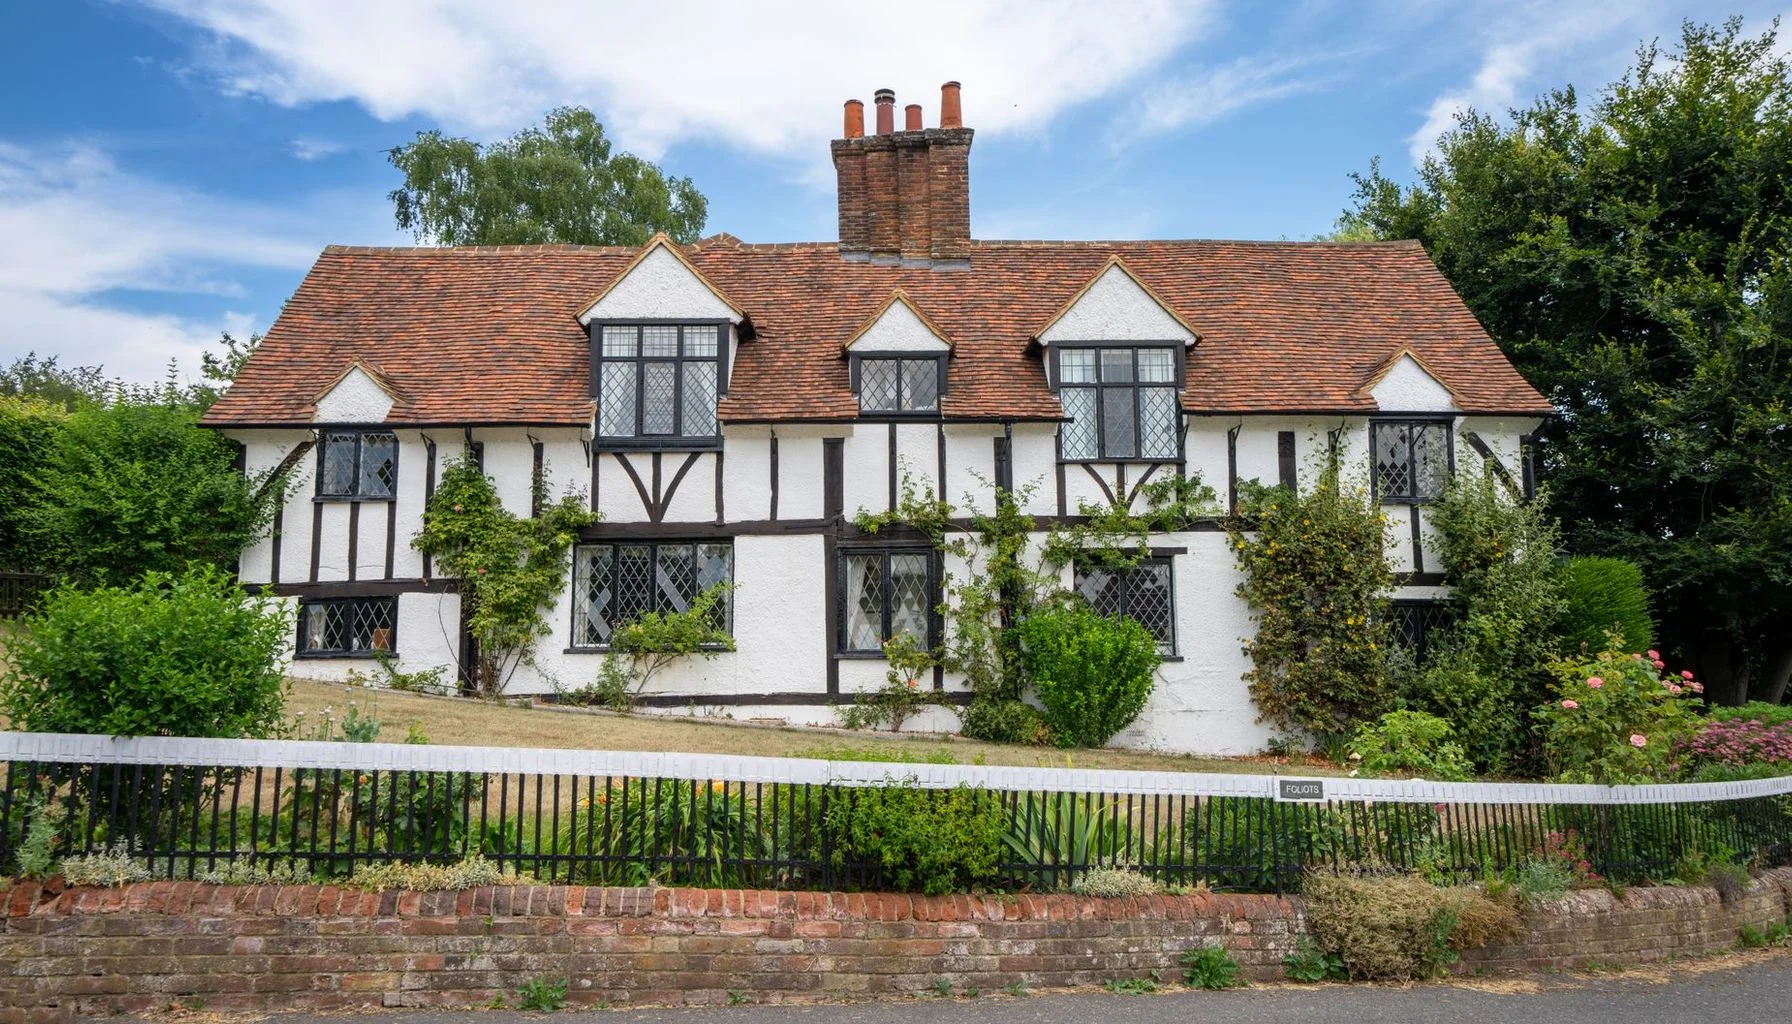
    Recent research indicates that over 1.5 million homes in the UK are classified as ‘unmortgageable’ by mainstream lenders, significantly impacting the mortgage market. This situation arises from various factors including construction type, lease length, and property condition, which restrict many buyers from securing standard mortgage finance.

    TL;DR: More than 1.5 million UK homes are deemed unfit for standard mortgages, affecting 6% of residential properties; this limits financing options for many potential buyers.

    What Makes a Home Unmortgageable?

    Properties can be deemed unmortgageable for several reasons. Common examples include thatched cottages, high-rise flats, and homes situated near commercial premises. Additionally, properties lacking essential amenities like functioning kitchens or bathrooms often fall into this category. These factors contribute to lenders’ reluctance to finance such properties, leaving many buyers without traditional mortgage options.

    Who Is Affected by This Issue?

    The implications of having 1.5 million homes classified as unmortgageable extend to various groups, including first-time buyers, investors, and landlords. A significant portion of buyers—44%—believe that these properties offer better value compared to more conventional homes. Among those considering these properties, 31% are motivated by the opportunity to renovate or restore, while 28% aim to increase property value before selling for profit.

    What This Means for the Mortgage Market

    For prospective buyers and investors, the classification of homes as unmortgageable presents both challenges and opportunities. Many buyers are drawn to the lower purchase prices associated with these properties, with 28% citing this as their primary motivation. For buy-to-let investors, the prospect of rental income is a significant incentive, with 35% of respondents highlighting this as their main attraction.

    However, the challenges are evident; over 21% of respondents reported having mortgage applications rejected, and 32% found themselves with a limited pool of lenders willing to consider their applications. This situation underscores the need for buyers to be well-informed about the risks and rewards involved in pursuing unmortgageable properties.

    What Should Buyers Watch Next?

    As the mortgage market continues to evolve, potential buyers interested in unmortgageable properties should stay informed about changes in lending criteria and seek out alternative financing options. Engaging with specialist lenders or exploring renovation loans may provide viable pathways for securing funding. Additionally, understanding the local property market and assessing the potential for value appreciation will be important for making informed investment decisions.

    Frequently asked questions

    What types of properties are typically classified as unmortgageable?

    Properties such as thatched cottages, high-rise flats, and those lacking essential amenities like kitchens or bathrooms are often deemed unmortgageable by mainstream lenders.

    How can buyers secure financing for unmortgageable properties?

    Buyers can explore alternative financing options, such as specialist lenders or renovation loans, to secure funding for unmortgageable properties.

  • Paragon Cuts Buy-to-Let Rates: Key Updates for Landlords

    Paragon Cuts Buy-to-Let Rates: Key Updates for Landlords

    Paragon Bank has announced a reduction in rates across a selection of five-year fixed-rate buy-to-let mortgages. This move is significant for landlords as it reflects recent changes in swap rates, offering more competitive financing options.

    TL;DR: Paragon Bank has reduced rates on five-year fixed-rate buy-to-let mortgages, impacting landlords seeking better financing options; the refreshed range includes products for various LTVs and cashback offers.

    What Changes Have Been Made to Buy-to-Let Rates?

    The updated offering from Paragon includes various products available at different loan-to-value (LTV) ratios. The range features options designed for properties with varying energy performance certificate (EPC) ratings. Additionally, the refreshed products include options for houses in multiple occupation (HMOs) and multi-unit blocks (MUBs).

    Who Benefits from These Rate Cuts?

    This rate reduction primarily benefits landlords looking to finance their buy-to-let properties. The new product range includes options with nil-fee, percentage-fee, and fixed-fee structures, along with selected products offering cashback. This flexibility allows landlords to choose a mortgage that best fits their financial strategy.

    What This Means for Landlords

    For landlords, the reduction in rates could lead to significant savings over the term of the mortgage. With the introduction of competitive rates, particularly for environmentally friendly properties, landlords may find it easier to manage their cash flow and invest in energy-efficient upgrades. As the market adjusts, landlords should keep an eye on further rate movements and consider how these changes might impact their investment strategies.

    Frequently asked questions

    What are the new rates for buy-to-let mortgages?

    The new rates for five-year fixed-rate buy-to-let mortgages from Paragon include options for green mortgages and HMOs.

    How can landlords benefit from these rate cuts?

    Landlords can benefit from lower borrowing costs, flexible fee options, and potential cashback offers, making it easier to finance their properties.

  • Mortgage Rates Rise Again: What Borrowers Should Know

    Mortgage Rates Rise Again: What Borrowers Should Know

    The UK mortgage market is experiencing another wave of rate hikes, with major lenders increasing their rates for residential and buy-to-let mortgages. This trend follows a spike in oil prices, which has raised inflation concerns and subsequently affected mortgage funding costs.

    TL;DR: Major lenders like HSBC, Halifax, and Santander have raised mortgage rates by up to 0.20%; borrowers and landlords should prepare for increased borrowing costs.

    Which lenders have increased their mortgage rates?

    HSBC has raised rates for both residential and buy-to-let mortgages for the second time this week. Halifax followed suit, increasing rates by up to 0.15% for home movers and first-time buyers, and by 0.20% for remortgaging customers. Santander also announced rate hikes of 0.15%, with some products seeing increases of 0.19%. These adjustments reflect the ongoing volatility in the financial markets.

    How do rising oil prices affect mortgage rates?

    The recent surge in oil prices, which reached $100 per barrel, has direct implications for inflation expectations. Although prices have since eased below $90, the initial spike has prompted lenders to adjust their mortgage rates in anticipation of rising costs. Anthony McQuilliam from Bolt Mortgages highlighted how quickly lenders can reprice their products in response to market changes, indicating that borrowers need to stay alert.

    What does this mean for borrowers and landlords?

    For borrowers, these rate increases mean higher monthly repayments, which could strain budgets, particularly for first-time buyers and those looking to remortgage. Landlords may also feel the impact as buy-to-let mortgage rates rise, potentially affecting rental yields and overall profitability. It is essential for both groups to reassess their financial strategies and consider locking in fixed rates if possible.

    What should borrowers watch for next?

    As the Moneyfacts Average New Mortgage Rate has climbed from 5.47% to 5.55% in just a week, borrowers should keep a close eye on further rate changes. Monitoring inflation trends and oil prices will be important, as these factors will likely influence future mortgage rates. Additionally, consulting with mortgage brokers can provide tailored advice based on individual financial situations.

    Frequently asked questions

    Will mortgage rates continue to rise?

    Given the current inflationary pressures and rising oil prices, it is likely that mortgage rates will continue to increase in the near term.

    How can I protect myself from rising mortgage costs?

    Consider locking in a fixed-rate mortgage to secure your payments against future rate hikes, and consult a mortgage broker for personalized advice.

  • Bank of England Maintains Mortgage Rates at 3.75%

    Bank of England Maintains Mortgage Rates at 3.75%

    The Bank of England has decided to keep interest rates steady at 3.75%, marking the fifth consecutive meeting where no changes were made. This decision comes as the Bank continues to address inflationary pressures exacerbated by geopolitical tensions in the Middle East.

    TL;DR: The Bank of England’s Base Rate remains at 3.75%, impacting borrowers and investors alike; with indications of potential rate hikes ahead, those in the mortgage market should prepare for possible increases.

    What does the Bank’s decision mean for mortgage borrowers?

    For those currently on tracker mortgages, the unchanged Bank Rate means their repayments will remain the same for now. However, experts warn that with the possibility of future rate increases, borrowers should evaluate their financial readiness for potential hikes. David Hollingworth from L&C Mortgages suggests that tracker customers should consider how they might manage increased payments if rates rise.

    How will this affect those looking to remortgage or buy a home?

    For individuals considering remortgaging or purchasing a property, today’s announcement signals a cautious yet uncertain outlook. The fact that three members of the Monetary Policy Committee voted for a rate increase indicates a growing concern about inflation and suggests that further rate hikes could occur before the year ends. Laura Suter, director of personal finance at AJ Bell, points out that recent trends show lenders have started raising rates, which could impact new mortgage deals.

    What are the implications for landlords and investors?

    Landlords and property investors should also be aware of the evolving interest rate environment. With rates potentially on the rise, the cost of borrowing could increase, affecting investment decisions and cash flow. The current climate may lead to higher mortgage costs for buy-to-let properties, influencing rental pricing and overall investment strategies.

    What should you watch for in the coming months?

    As the situation develops, borrowers and investors should keep a close eye on the Bank of England’s future meetings and economic indicators related to inflation. The split vote within the Monetary Policy Committee suggests that the appetite for rate increases is growing, which could lead to significant changes in the mortgage market. Monitoring lender activity and market trends will be important for making informed decisions.

    Frequently asked questions

    Will my mortgage payments change after this announcement?

    No immediate changes are expected for those on tracker mortgages, as the Bank Rate remains unchanged at 3.75%. However, future rate hikes could affect payments.

    What should I do if I’m looking to remortgage?

    If you’re considering remortgaging, it’s advisable to act sooner rather than later, as lenders are already beginning to increase rates. Assess your options and consider locking in a deal before potential future hikes.

  • July Updates in the UK Mortgage Market for Landlords

    July Updates in the UK Mortgage Market for Landlords

    The buy-to-let (BTL) mortgage market has seen significant activity this month, with various lenders adjusting their offerings. These changes reflect a competitive environment aimed at attracting landlords and investors, particularly in the wake of evolving property needs and investment strategies.

    TL;DR: Zephyr Homeloans has cut its HMO and MUFB tracker rates; landlords and expat borrowers will benefit from new competitive rates and options across several lenders.

    What are the latest changes in the mortgage market?

    Zephyr Homeloans has made notable reductions to its lifetime tracker rates for large houses in multiple occupation (HMO) and multi-unit freehold blocks (MUFB). The new rates apply to properties with 7-12 bedrooms/units, applicable up to certain loan to value (LTV) ratios with a maximum loan size and product fee. For higher LTVs, the rates have also been adjusted accordingly.

    Tipton & Coseley Building Society has introduced a new two-year fixed rate for expat BTL borrowers, available up to a certain LTV with an arrangement fee. This product is aimed at expats residing in Financial Action Task Force-approved countries and the UAE, providing more options for overseas investors.

    Aldermore Dudley Building Society has announced reductions across its BTL and residential ranges. For instance, their two-year fixed BTL product at a specific LTV is now available at a lower rate. Paragon Bank has also updated its BTL BBR tracker range, introducing a new fee product for single self-contained properties at a specified LTV, priced from BBR plus a certain percentage.

    How do these changes impact landlords and investors?

    The reductions in rates and the introduction of new products provide landlords with more competitive financing options, potentially lowering their overall borrowing costs. For example, CHL Mortgages has launched a light refurbishment range for investors looking to upgrade properties, with two-year fixed rates starting from a specific percentage for single dwelling properties up to a certain LTV.

    Additionally, Kensington Mortgages has lowered its minimum property valuation for its BTL range, now accepting properties valued from a lower threshold for LTVs of 75% or lower. This change enhances access for landlords seeking to purchase or remortgage lower-valued properties, a segment often overlooked in the past.

    What should brokers and borrowers watch for next in the mortgage market?

    Brokers should monitor these developments closely, as lenders continue to adapt their offerings in response to market demands. Fleet Mortgages has announced it will now consider joint applications involving foreign nationals, provided at least one applicant holds a British passport or has settled status. This expands the market for international investors looking to enter the UK property scene.

    Moreover, the introduction of dedicated pricing bands for larger loans by Tipton & Coseley Building Society indicates a shift towards catering to high-net-worth individuals and larger investment portfolios.

    What this means for expat borrowers

    Expat borrowers are set to benefit significantly from the new offerings, particularly the competitive rates introduced by Tipton & Coseley Building Society. The ability to secure a two-year fixed rate up to a certain LTV opens doors for those looking to invest in UK property from abroad. This is particularly relevant as the UK remains an attractive market for overseas investors, despite global economic uncertainties.

    Frequently asked questions

    What types of properties are eligible for the new HMO and MUFB rates?

    The new rates from Zephyr Homeloans apply to large houses in multiple occupation (HMO) and multi-unit freehold blocks (MUFB) with 7-12 bedrooms or units, enhancing financing options for landlords in these categories.

    How can landlords benefit from the light refurbishment range?

    Landlords can take advantage of CHL Mortgages’ light refurbishment range to finance improvements such as installing new bathrooms, kitchens, or updating fixtures and fittings, starting from competitive rates for single dwelling properties.

  • Key Updates in the BTL Mortgage Market This Month

    Key Updates in the BTL Mortgage Market This Month

    The buy-to-let (BTL) mortgage market has seen significant activity recently, with various lenders adjusting their rates and criteria. These changes are important for landlords and investors looking to navigate the evolving market of property finance.

    TL;DR: Zephyr Homeloans has cut its HMO and MUFB tracker rates, while Tipton & Coseley Building Society introduces a new expat BTL product; these updates could benefit landlords and expat investors.

    What are the latest rate changes in the mortgage market?

    Zephyr Homeloans has reduced its lifetime tracker rates for large HMOs and MUFBs. For properties with 7-12 bedrooms or units, rates now start for loans up to 65% loan to value (LTV), with a maximum loan size of £2 million and a 3% product fee. At 75% LTV, the rate is now available for a maximum loan size of £1.5 million, also with a 3% product fee. Additionally, Zephyr will lend to HMOs and MUFBs located above or adjacent to commercial premises, up to a maximum of 75% LTV.

    Tipton & Coseley Building Society has launched a new two-year fixed rate product for expat BTL borrowers, available up to 70% LTV. This product has an arrangement fee and is accessible to expats residing in countries on the Financial Action Task Force approved list, as well as the UAE (with some exceptions). The lender has also introduced a 65% LTV option for more flexibility and a dedicated pricing band for loans between £10 million and £25 million. Rates have been reduced for both new customers and product transfers, with a notable example being a two-year fixed rate at 75% LTV in the £1 million to £2 million band, now priced with a fee.

    How are lenders adjusting their offerings in the mortgage market?

    Aldermore Dudley Building Society has announced reductions across its BTL, residential, holiday let, and expat ranges. For instance, its two-year fixed BTL product at 80% LTV is now available at a lower rate. Similarly, a two-year fixed holiday let product at the same LTV is now priced lower.

    Paragon Bank has updated its BTL BBR tracker range, introducing a new product with a fee for single self-contained properties at 75% LTV. Additionally, CHL Mortgages has launched a light refurbishment range aimed at investors looking to make improvements to properties. Two-year fixed rates in this range start for single dwelling properties up to 75% LTV with a fee, and for small HMO and MUFB properties with up to six bedrooms or units.

    What does this mean for landlords and investors in the mortgage market?

    The recent changes in the BTL mortgage market present both opportunities and challenges for landlords and investors. With lower rates and more flexible options, landlords can potentially reduce their borrowing costs and enhance their investment portfolios. For example, the reduction in rates from Aldermore and Zephyr Homeloans could make financing more accessible, particularly for larger properties or those adjacent to commercial premises.

    Moreover, the introduction of new products for expat investors by Tipton & Coseley Building Society expands the market for those looking to invest in UK property from abroad. This could lead to increased competition among lenders, potentially driving rates down further and benefiting borrowers.

    Frequently asked questions

    What should landlords consider when choosing a BTL mortgage?

    Landlords should evaluate the loan-to-value ratio, interest rates, fees, and the specific terms of each mortgage product. It’s essential to consider the type of property being financed, as different lenders may have varying criteria for HMOs, MUFBs, and standard buy-to-let properties.

    How can I stay updated on mortgage rates and products?

    Regularly check mortgage comparison websites and lender announcements to stay informed about the latest rates and product offerings. Resources like mortgage rate comparison tools can help you find the best deals available in the market.

  • Buy-to-Let Watch: Understanding Tenant Fraud Risks

    Buy-to-Let Watch: Understanding Tenant Fraud Risks

    Recent findings reveal that tenant fraud is significantly impacting UK landlords, costing them an estimated £266 million each month. With most landlords unable to recover these losses, understanding the rise in fraudulent tenancy applications is important for anyone involved in the buy-to-let sector.

    TL;DR: Tenant fraud is costing UK landlords £266 million monthly; with a 140% increase in detected fraud cases, landlords must be vigilant to protect their investments.

    What is the Current State of Tenant Fraud in Buy-to-Let?

    Research shows that tenant fraud is on the rise, with incidences increasing from just over one case per 1,000 applications in 2022 to 2.9 cases per 1,000 in 2023. This represents a staggering 140% increase year-on-year. The prevalence of fraudulent activities is concerning, particularly as landlords face challenges in recovering losses.

    How Are Fraudulent Activities Being Executed in the Buy-to-Let Market?

    According to reports, 94% of tenant fraud cases involve the submission of fake documents, with doctored bank statements being the most common tactic. This trend highlights the need for landlords and letting agents to implement robust verification processes to identify fraudulent applications early on.

    What Are the Legal Implications for Buy-to-Let Landlords?

    The Renters’ Rights Act 2025 has made it more challenging for landlords to reclaim possession of their properties. With the abolition of Section 21 notices, landlords can no longer evict tenants without a specific legal reason, and the notice periods for Section 8 have been extended to as long as four months in many cases. This legislative shift means that landlords must be more proactive in screening tenants to avoid potential issues.

    What This Means for Landlords and Brokers in the Buy-to-Let Sector

    Landlords must take tenant fraud seriously, as around 20% of landlords reported being victims of illegal subletting, and 8% have encountered fake financial information from prospective tenants. Brokers should incorporate discussions about tenant fraud into their advice for landlords, as this knowledge can help clients mitigate risks. While there is a legal route available under Ground 17 of the Housing Act for cases of tenancy obtained through false statements, the process is discretionary and requires clear evidence, which is not always readily available.

    Frequently asked questions

    What steps can landlords take to prevent tenant fraud?

    Landlords can implement thorough tenant screening processes, including verifying financial documents and conducting background checks to ensure the authenticity of applications.

    How can brokers assist landlords in dealing with tenant fraud?

    Brokers can provide valuable advice on best practices for tenant screening and educate landlords about the legal implications of tenant fraud, helping them to protect their investments effectively.

  • Buy-to-Let Watch: Addressing Tenant Fraud Challenges

    Buy-to-Let Watch: Addressing Tenant Fraud Challenges

    Tenant fraud is becoming a significant issue for buy-to-let landlords in the UK, with recent research revealing that it costs them an estimated £266 million each month. This alarming trend highlights the urgent need for landlords and brokers to be vigilant in their tenant screening processes.

    TL;DR: Tenant fraud is costing UK landlords £266 million monthly; with a 140% increase in detected fraud cases, landlords must enhance their tenant verification methods.

    How Has Tenant Fraud Increased Recently?

    Research conducted by Goodlord indicates a troubling rise in tenant fraud, with detected cases increasing from just over one per 1,000 tenancy applications in 2022 to 2.9 per 1,000 in 2023. This represents a staggering 140% year-on-year increase. The most common method employed by fraudsters involves the use of doctored bank statements, with fake documents constituting 94% of all fraud cases. The Cifas Fraudscape 2026 report corroborates these findings, noting that over 444,000 cases were recorded in 2025, marking the highest annual total to date.

    What Are the Implications of the Renters’ Rights Act 2025 for Buy-to-Let Landlords?

    The introduction of the Renters’ Rights Act 2025 has heightened the stakes for landlords. With the abolition of Section 21, landlords can no longer regain possession of their properties without a specific legal ground. Additionally, notice periods under Section 8 have been extended, sometimes up to four months. This legislative change means that landlords must be more proactive in their tenant vetting processes to avoid potential losses due to fraud.

    What Should Landlords and Brokers Do About Buy-to-Let Fraud?

    Landlords and brokers should incorporate discussions about tenant fraud into their advisory conversations. Understanding the risks associated with fraudulent applications is important for protecting investments. While there is a legal route available for landlords through Ground 17 of the Housing Act, which addresses tenancies obtained through false statements, this process is discretionary and requires substantial evidence, making it far from a guaranteed solution.

    Recent research indicates that around 20% of landlords have reported being victims of illegal subletting, while 8% have encountered fake financial information from prospective tenants. Brokers who are equipped with knowledge about these issues can better assist their clients in navigating the complexities of tenant fraud.

    What This Means for Buy-to-Let Landlords

    For landlords, the rise in tenant fraud poses a significant risk to their financial stability. With the inability to swiftly regain possession of properties and the increasing prevalence of fraudulent applications, it is imperative for landlords to implement robust tenant screening processes. This includes verifying financial information and conducting thorough background checks. By doing so, landlords can mitigate potential losses and ensure their investments are safeguarded.

    Frequently asked questions

    What are the most common tactics used in tenant fraud?

    Doctored bank statements are the most prevalent method, with 94% of fraud cases involving fake documents. This highlights the importance of thorough verification processes for landlords.

    How can landlords protect themselves from tenant fraud?

    Landlords can protect themselves by implementing stringent tenant screening processes, including verifying financial information and conducting comprehensive background checks to identify potential fraud.

  • Afin Bank Hits £135M in Buy-to-Let Mortgage Approvals

    Afin Bank Hits £135M in Buy-to-Let Mortgage Approvals

    Afin Bank has marked its first anniversary by achieving a significant milestone of £135 million in mortgage approvals within just one year. This accomplishment highlights the growing demand for tailored lending solutions, particularly for underserved borrowers in the UK property market.

    TL;DR: Afin Bank has approved £135 million in mortgages in its inaugural year; this indicates a strong demand for buy-to-let mortgages and support for non-traditional borrowers.

    How Does Afin Bank Support Buy-to-Let Borrowers?

    Initially focused on providing mortgages to foreign nationals with valid work visas, Afin Bank has broadened its services to accommodate a diverse range of borrowers. This includes self-employed individuals, contractors, qualified professionals, and those with complex income situations. The expansion reflects a growing recognition of the need for flexible lending solutions in the current economic climate.

    What Mortgage Products Does Afin Bank Offer?

    Afin Bank provides a variety of mortgage products, including residential and buy-to-let mortgages, as well as a newly launched regulated bridging service for properties in England and Wales. This range of options allows borrowers to choose solutions that best fit their financial situations and property investment goals.

    What This Means for Borrowers and Landlords

    For landlords and potential property investors, Afin Bank’s commitment to £135 million in mortgage approvals signals a positive shift in the lending market. As mainstream lenders tighten their criteria, Afin Bank’s approach provides an alternative for those whose financial profiles may not meet traditional lending standards. This is particularly relevant for buy-to-let investors looking to expand their portfolios or first-time buyers aiming to enter the market.

    What Should Borrowers Watch Next?

    As economic conditions evolve, borrowers should keep an eye on how lenders adjust their offerings. Afin Bank’s growth indicates a potential shift towards more inclusive lending practices. Borrowers may benefit from exploring options like Afin’s buy-to-let mortgages, especially as they cater to those with unique financial circumstances. Additionally, monitoring changes in interest rates and lending criteria will be important for making informed decisions.

    Frequently asked questions

    What types of buy-to-let mortgages does Afin Bank offer?

    Afin Bank offers both residential and buy-to-let mortgage products, catering to a range of borrower needs, including those with complex income situations.

    Who can benefit from Afin Bank’s mortgage services?

    Borrowers who may find it challenging to secure financing from mainstream lenders, such as self-employed individuals, contractors, and foreign nationals, can benefit from Afin Bank’s tailored mortgage solutions.

  • UK Mortgage Market Update: Rates Rise and New Rules Impact Borrowers

    UK Mortgage Market Update: Rates Rise and New Rules Impact Borrowers

    The UK mortgage market is experiencing significant changes as lenders adjust rates and new affordability rules come into play. Recent data indicates a surge in borrowers switching lenders, driven by the Financial Conduct Authority’s (FCA) updated affordability assessments, which are enabling more consumers to seek better mortgage deals.

    TL;DR: 98% of modified affordability assessments were used for external remortgages in Q1 2026; major lenders like Barclays and Santander are raising mortgage rates by up to 20 basis points.

    What are the recent changes in mortgage rates?

    Several major lenders have announced increases in their mortgage rates, with Barclays, Halifax, HSBC, TSB, and Skipton raising selected rates by up to 20 basis points. NatWest has also joined this trend, increasing rates for residential and buy-to-let mortgages. These adjustments are primarily a response to rising swap rates, which are pushing up funding costs across the mortgage market.

    How are affordability rules influencing borrower behaviour?

    The FCA’s recent changes to affordability assessments have made it easier for borrowers to switch to new lenders. Research from Stonebridge reveals that 98% of modified assessments in Q1 2026 were used for external remortgages. This shift indicates that more borrowers are taking advantage of competitive rates offered by different lenders, rather than remaining with their current providers.

    What does this mean for borrowers and landlords?

    For borrowers, the current environment presents both opportunities and challenges. Those looking to remortgage may find it beneficial to explore options with different lenders, especially as the new affordability rules provide greater flexibility. However, with rising rates, it is important for borrowers to act swiftly to secure lower rates before further increases occur.

    Landlords should also be aware of the changing market. The increases in buy-to-let mortgage rates may impact investment strategies, particularly for those relying on financing for property acquisitions. It is advisable for landlords to reassess their portfolios and consider the implications of higher borrowing costs on their overall investment plans.

    What new developments are occurring in the mortgage market?

    In addition to rate changes, several lenders are expanding their product offerings. For example, Santander is increasing fixed mortgage rates and introducing new 10-year fixed deals, along with additional options for new builds. Meanwhile, Vida has rebranded its later-life mortgage proposition to Next Chapter Lending, aiming to support older borrowers with clearer affordability guidance.

    Furthermore, Finova is launching an AI-powered tool designed to streamline the mortgage application process for brokers, allowing them to submit applications across lender portals without the need for manual data entry. This innovation could enhance efficiency in the mortgage process, benefiting both brokers and borrowers alike.

    Frequently asked questions

    What should I do if I want to switch my mortgage?

    If you’re considering switching your mortgage, start by reviewing your current deal and comparing it with offers from other lenders. With the new affordability rules in place, it may be easier to qualify for better rates. Consult with a mortgage broker to explore your options and ensure you make an informed decision.

    How will rising mortgage rates affect my borrowing capacity?

    Rising mortgage rates can reduce your borrowing capacity, as lenders typically assess your ability to repay based on current interest rates. Higher rates mean higher monthly repayments, which could limit the amount you can borrow. It’s essential to factor in these changes when planning your mortgage strategy.