Author: David Sampson

  • Limited Companies and the Mortgage Market: What Landlords Need to Know

    Limited Companies and the Mortgage Market: What Landlords Need to Know

    Recent trends indicate that not all landlords need to establish a limited company to manage their properties effectively. As the mortgage market evolves, understanding the implications of ownership structures is important for landlords navigating financial challenges.

    TL;DR: A significant percentage of buy-to-let purchases are made through limited companies; this shift highlights the growing appeal of corporate ownership among landlords facing rising tax burdens.

    Why Are More Landlords Choosing Limited Companies?

    Hamptons reported a notable increase in the number of companies set up to hold rental properties. The trend is largely driven by changes in tax regulations affecting personal ownership of rental properties.

    What Are the Tax Implications for Landlords in the Mortgage Market?

    Landlords who own properties personally face limitations on tax relief for mortgage interest. Personal ownership allows only a basic-rate tax credit on finance costs. In contrast, limited companies can deduct mortgage interest before paying corporation tax. This disparity makes the corporate route increasingly attractive, especially for landlords with higher incomes who may be subject to higher income tax rates.

    How Do Recent Changes Affect Property Transfers?

    Transferring a property from personal ownership to a limited company is treated as both a disposal and a purchase, triggering capital gains tax liabilities and stamp duty land tax (SDLT) charges. The SDLT for additional properties now includes a surcharge for company purchases, adding to the financial burden of such transfers.

    What This Means for Landlords and Investors in the Mortgage Market

    The increasing number of landlords opting for limited companies indicates a shift in strategy to mitigate tax liabilities. A significant percentage of mortgaged buy-to-let purchases are made through limited companies, highlighting the need for landlords to evaluate their ownership structures carefully. The freeze on personal tax allowances has further complicated matters, pushing more landlords into higher tax brackets. As a result, the corporate route may provide a more favorable financial outlook for many property owners.

    Frequently Asked Questions

    What are the benefits of owning rental properties through a limited company?

    Owning rental properties through a limited company allows landlords to fully deduct mortgage interest from taxable profits, potentially resulting in lower overall tax liabilities compared to personal ownership.

    What should landlords consider before transferring properties to a limited company?

    Landlords should be aware of the capital gains tax and stamp duty implications of transferring properties to a limited company, as these can significantly impact the financial viability of such a move.
  • Record £108m Property Finance in the UK Mortgage Market

    Record £108m Property Finance in the UK Mortgage Market

    Word On The Street has achieved a remarkable milestone by arranging a record £108 million in property finance over the past year. This significant growth highlights the resilience of the UK mortgage market amid various challenges, making it an important development for landlords, borrowers, and investors alike.

    TL;DR: Word On The Street arranged a record £108 million in property finance, reflecting a 62% annual growth; this surge impacts landlords and investors seeking financing options.

    How Did Word On The Street Achieve This Growth?

    The firm reported a 130% year-on-year increase in the number of cases facilitated, completing a total of 239 transactions. This included 130 buy-to-let (BTL) cases, 82 bridging loans, 16 development finance cases, and 11 commercial mortgages. The average loan size reached £462,637, showcasing the firm’s ability to cater to a diverse range of financing needs.

    What Does This Mean for the Mortgage Market?

    The substantial growth in property finance arranged by Word On The Street is indicative of a robust demand for mortgage products, particularly in the buy-to-let sector. For landlords, this means more accessible financing options as lenders become increasingly willing to support property investments. Additionally, the 75% jump in total revenue to £1.8 million signals a healthy market environment, which could encourage further investment in property.

    What Trends Should Borrowers Watch in the Mortgage Market?

    As the mortgage market continues to evolve, borrowers should keep an eye on the increasing competition among lenders, which may lead to more favourable mortgage rates. With the current trend of rising property finance arrangements, it’s essential for potential borrowers to stay informed about current mortgage rates and explore mortgage rate comparison tools to find the best deals available.

    Frequently asked questions

    What types of cases did Word On The Street finance?

    Word On The Street financed a range of cases, including 130 buy-to-let, 82 bridging loans, 16 development finance, and 11 commercial mortgage cases.

    How has the mortgage market responded to recent challenges?

    The mortgage market has shown resilience, with firms like Word On The Street reporting significant growth in both the value and number of cases facilitated, indicating strong demand for property finance.

  • Record High in Company Landlords: What It Means for You

    Record High in Company Landlords: What It Means for You

    The number of company landlords in the UK has surged, with nearly 14,000 new landlord businesses registered in just the first five months of 2026. This trend, which shows no signs of slowing, could significantly impact the buy-to-let market and the strategies of current and prospective landlords.

    TL;DR: Nearly 14,000 new landlord businesses were registered in 2026’s first five months; this marks a 70% increase over the five-year average, indicating a booming buy-to-let sector.

    Why Are More Landlords Choosing Company Structures?

    The trend towards establishing landlord businesses has been accelerating since the introduction of the 3% stamp duty surcharge on additional properties in April 2016. This policy prompted a nearly 59% increase in new registrations over the following two years. The benefits of operating as a company include potential tax advantages and limited liability, making it an attractive option for many investors.

    How Does This Growth Compare Historically?

    Analysis shows that the number of new buy-to-let companies has skyrocketed by 1,700% since the year 2000, when only 1,882 were incorporated. In fact, the current decade has already seen more new landlord businesses registered than the entire period from 2000 to 2019. Last year alone, 34,128 new buy-to-let businesses were established, nearly 70% higher than the five-year average of 23,549.

    What Regions Are Seeing the Most Growth?

    While London has historically been the largest market for buy-to-let registrations, recent data indicates a shift in this trend. The devolved nations are experiencing dramatic growth, with Scotland’s annual registrations more than tripling since 2020, up 171%. Northern Ireland and Wales are also seeing substantial increases, with annual registrations rising by 148% and 144%, respectively. Scotland now boasts over 2,100 new landlord companies each year, a significant jump from fewer than 400 in 2015.

    What This Means for Current and Prospective Landlords

    The rapid growth in company landlords presents both opportunities and challenges. For existing landlords, this could lead to increased competition in the rental market, potentially impacting rental yields. New landlords entering the market may benefit from the established frameworks and insights gained from the surge in registrations. Additionally, as the market diversifies beyond London, investors may find new opportunities in regions that are experiencing significant growth.

    Frequently Asked Questions

    What are the benefits of registering as a company landlord?

    Registering as a company landlord can provide tax advantages, limited liability, and a more structured approach to property management, which can be beneficial for larger portfolios.

    How can I stay updated on mortgage rates for buy-to-let properties?

    For the latest information on mortgage rates for buy-to-let properties, consider checking current mortgage rates or comparing mortgage rates to find the best options available.

  • Leeds Building Society Launches 98% LTV Mortgage

    Leeds Building Society Launches 98% LTV Mortgage

    Leeds Building Society has introduced a new mortgage product aimed at first-time buyers, allowing them to secure loans of up to 98% of a property’s value. This initiative is designed to make homeownership more accessible for individuals with smaller deposits, addressing a significant barrier for many potential buyers.

    TL;DR: The new Start Mortgage from Leeds Building Society offers first-time buyers a 98% loan-to-value option; this product aims to ease the financial burden of entering the property market.

    What is the Start Mortgage?

    The Start Mortgage is a first-time buyer mortgage that combines a high loan-to-value (LTV) ratio with flexible income requirements. Borrowers can access loans of up to five times their income, which is notably higher than the standard lending cap of 4.5 times. This mortgage is available through brokers and features a minimum income threshold of £30,000, with a maximum loan size capped at £500,000.

    How Does This Mortgage Work?

    For example, a single or joint applicant with a household income of £49,000 and a deposit of £5,000 could secure a mortgage of £245,000 to purchase a home valued at £250,000, resulting in a 98% LTV. The mortgage is offered as a five-year fixed-rate option at 5.65%, providing stability in monthly payments during the initial term.

    What This Means for First-Time Buyers

    The introduction of the Start Mortgage is particularly significant for first-time buyers who have struggled to save for larger deposits. With the requirement of only £5,000 as a deposit, this product opens doors for many individuals who may have previously felt priced out of the housing market. The combination of a higher LTV and increased income multiples helps to address affordability issues, which remain a major concern for potential homeowners.

    What Should Borrowers Watch Next?

    As the housing market continues to evolve, first-time buyers should keep an eye on similar products that may emerge from other lenders. The Start Mortgage reflects a growing trend among financial institutions to offer more flexible lending solutions. Borrowers should also consider using tools like a mortgage calculator to assess their financial readiness and explore various mortgage options available to them.

    Frequently asked questions

    What is the maximum loan amount for the Start Mortgage?

    The maximum loan amount available under the Start Mortgage is £500,000.

    What is the minimum income requirement for this mortgage?

    To qualify for the Start Mortgage, applicants must have a minimum household income of £30,000.

  • Getting a Mortgage on Timber-Built Properties Explained

    Getting a Mortgage on Timber-Built Properties Explained

    Securing a mortgage for a timber-built property can be challenging, but it is possible. Understanding the nuances of timber construction is essential for potential borrowers, as lenders often have specific concerns regarding these types of properties.

    TL;DR: Mortgages for timber-built properties are available but often come with restrictions; fully timber constructions may require larger deposits and specialist lenders.

    What Types of Timber Construction Are There?

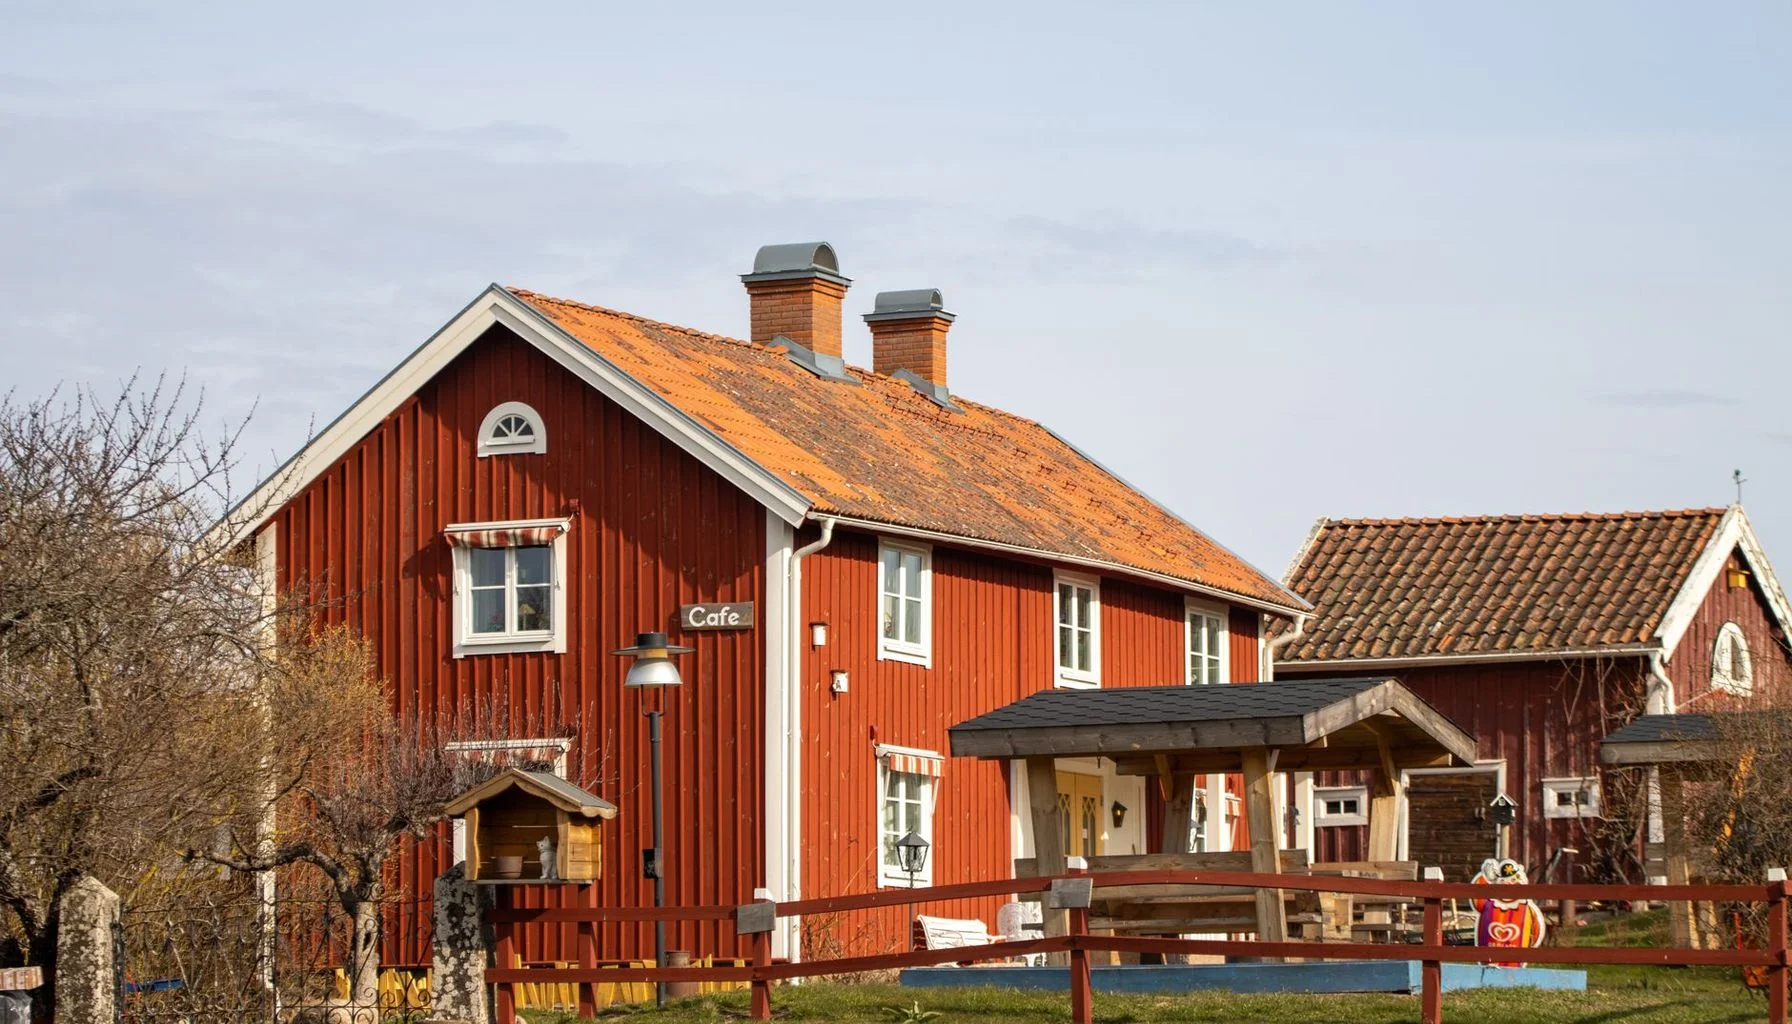
    Timber properties can vary significantly in construction style, which influences mortgage eligibility. Fully timber structures, such as log cabins, typically face more scrutiny from lenders. In contrast, properties constructed with Swedish timber or chalet-style homes are classified as ‘non-standard construction.’ These classifications affect lender appetite and the terms of any mortgage offered.

    Why Are Timber-Built Properties More Difficult to Finance?

    Lenders often express concerns about several factors related to timber-built properties, including:

    • Fire Risk: Timber is more susceptible to fire damage, raising concerns about safety and insurance.
    • Durability and Lifespan: The longevity of timber structures can be questioned, impacting resale value.
    • Resale Value: If a property is repossessed, it may be harder to sell, making lenders cautious.
    • Maintenance Requirements: Timber properties may require more upkeep, which can deter some buyers.

    What This Means for Borrowers Seeking a Mortgage

    For those looking to purchase a timber-built property, it’s important to be aware that standard high street lenders may not offer competitive rates. Instead, borrowers might need to seek out building societies or specialist lenders who have more flexible underwriting criteria. Factors such as the surveyor’s report, construction type, location, deposit size, and the borrower’s financial profile will all play significant roles in mortgage approval. For more information on mortgage options, check out our residential mortgages.

    Frequently Asked Questions

    Can I get a mortgage on a log cabin?

    Yes, but you may face challenges. Log cabins are often considered non-standard construction, which can limit lender options and require a larger deposit.

    What should I do if my broker has a limited panel of lenders?

    Consider consulting another broker who specializes in non-standard construction mortgages to explore more options and find a suitable lender.

  • Record £108m Property Finance Boosts UK Mortgage Market

    Record £108m Property Finance Boosts UK Mortgage Market

    Word On The Street has achieved a remarkable milestone by arranging a record £108 million in property finance over the past year, highlighting a significant shift in the UK mortgage market. This achievement not only reflects the firm’s resilience amid challenges but also signals growing opportunities for landlords, borrowers, and investors.

    TL;DR: Word On The Street arranged £108 million in property finance, marking a 62% annual growth; this surge indicates a thriving mortgage market, benefiting landlords and investors.

    What Factors Contributed to This Growth?

    The firm reported a 130% year-on-year increase in the number of cases facilitated, completing a total of 239 cases. This included 130 buy-to-let (BTL) mortgages, 82 bridging loans, 16 development finance cases, and 11 commercial mortgages. The average loan size was £462,637, showcasing the scale of financing available in the current market.

    How Does This Impact Landlords and Borrowers?

    This substantial increase in property finance can be particularly advantageous for landlords looking to expand their portfolios. The rise in buy-to-let cases indicates a robust demand for rental properties, which may lead to increased rental yields. For borrowers, the diverse range of finance options available, including bridging and development loans, provides flexibility and potential for growth in various property sectors.

    What This Means for the Mortgage Market

    The 75% jump in total revenue, reaching £1.8 million, underscores the firm’s success and the overall health of the mortgage market. As lenders become more competitive, borrowers may benefit from improved rates and terms. Investors should keep an eye on emerging trends in property finance, as this growth could lead to further opportunities in the mortgage market.

    Frequently asked questions

    What types of mortgages are currently in demand?

    There has been a notable demand for buy-to-let mortgages, bridging loans, and development finance, reflecting diverse investment strategies among borrowers.

    How can I stay updated on mortgage rates?

    For the latest information on mortgage rates, consider checking resources that provide regular updates on current mortgage rates and comparisons.

  • Landlords and Limited Companies in the Mortgage Market

    Landlords and Limited Companies in the Mortgage Market

    Recent trends indicate that not all landlords in the UK need to establish limited companies to manage their rental properties effectively. As the tax market evolves, many landlords are reassessing their structures and strategies to navigate the complexities of the mortgage market.

    TL;DR: A significant portion of buy-to-let purchases were made through limited companies; however, personal ownership can still be viable for certain landlords.

    Why Are More Landlords Choosing Limited Companies?

    Data from Hamptons reveals a notable rise in the number of landlords opting to set up limited companies to hold rental properties, with a substantial increase in new companies registered in recent years. This shift is largely attributed to changes in mortgage interest tax relief, which have made corporate structures more appealing.

    What Are the Tax Implications for Landlords?

    Landlords who own properties personally can only claim a basic-rate tax credit on their finance costs, which can be significantly less advantageous compared to the full interest deduction available to limited companies. Companies pay corporation tax on profits, while the income tax for individuals can rise to higher levels. As a result, the corporate route is becoming increasingly attractive for landlords looking to maximise their tax efficiency.

    What Should Landlords Consider Before Transferring Properties?

    Transferring an existing property into a limited company is treated as both a disposal and a purchase. This means landlords may incur capital gains tax upon transfer and face stamp duty land tax when moving the property into the company. The additional surcharge on stamp duty for additional properties further complicates this decision. Landlords may face significant tax liabilities if they decide to transfer properties into a corporate structure.

    What This Means for Landlords in the Mortgage Market

    Landlords must carefully evaluate their financial situations before deciding whether to establish a limited company. As the tax market continues to evolve, many landlords may find themselves in tighter financial positions. The freeze on personal tax allowances has also pushed more landlords into higher tax bands, making corporate ownership more appealing for some. However, for landlords with lower property portfolios or those close to retirement, remaining in personal ownership could still be a viable option.

    Frequently Asked Questions

    What are the benefits of owning rental properties through a limited company?

    Owning rental properties through a limited company allows landlords to deduct mortgage interest in full before paying corporation tax, which can be more tax-efficient than personal ownership. This structure also limits personal liability.

    How does the freeze on personal tax allowances affect landlords?

    The freeze on personal tax allowances has gradually pushed more landlords into higher tax brackets, increasing their tax burden and making the limited company route more attractive for tax efficiency.

  • Company Landlords Surge to Record High in 2026

    Company Landlords Surge to Record High in 2026

    The number of company landlords in the UK has reached unprecedented levels, with nearly 14,000 new landlord businesses registered in just the first five months of 2026. This trend underscores a significant shift in the property investment market, impacting landlords, borrowers, and investors alike.

    TL;DR: Nearly 14,000 new landlord businesses were registered in early 2026; this surge reflects a broader trend of increasing company ownership in the buy-to-let sector.

    What’s Driving the Surge in Company Landlords?

    Analysis from Companies House reveals that the total number of new buy-to-let businesses registered last year hit a record high of 34,128, marking a nearly 70% increase over the five-year average of 23,549 per year. The growth of company landlords has been particularly pronounced since the year 2000, with registrations soaring by 1,700%. This dramatic rise can be traced back to various factors, including tax incentives and regulatory changes that have made incorporating a property business more attractive.

    How Has the Market Changed Over Time?

    The introduction of the 3% stamp duty surcharge on additional properties in April 2016 triggered a significant spike in company registrations, with a nearly 59% increase in the two years that followed. The 2020s have already seen more new landlord businesses registered than the entire period from 2000 to 2019, indicating a robust trend towards incorporation among property investors.

    What This Means for Landlords

    For landlords, the rise in company registrations suggests a shift in strategy, with many opting to operate their rental properties through limited companies. This can offer various tax benefits, including the ability to deduct mortgage interest from profits before tax. Additionally, the regional market is changing, with Scotland, Northern Ireland, and Wales seeing substantial growth in new landlord companies. Scotland, for instance, has seen its annual registrations triple since 2020, indicating a growing appetite for property investment outside of London.

    What Should Investors Watch Next?

    Investors should keep an eye on ongoing changes in legislation and tax policies that may further influence the buy-to-let market. As the trend of company ownership continues to rise, understanding the implications of these changes will be important for both new and existing landlords. Additionally, monitoring regional market shifts can provide insights into emerging opportunities across the UK.

    Frequently asked questions

    What are the benefits of becoming a company landlord?

    Becoming a company landlord can offer significant tax advantages, such as the ability to deduct mortgage interest from profits before tax, which can lead to increased profitability.

    How has the growth of company landlords affected the rental market?

    The growth of company landlords has diversified the rental market, leading to increased competition and potentially influencing rental prices across different regions.

  • Understanding Mortgages for Timber-Built Properties

    Understanding Mortgages for Timber-Built Properties

    Obtaining a mortgage for a timber-built property can be challenging, but it is possible. The type of timber construction plays a significant role in determining mortgage availability and terms, which is important for prospective buyers and investors.

    TL;DR: Mortgages for timber-built properties exist but are often limited; fully timber structures may require larger deposits and specialist lenders.

    Can You Get a Mortgage on a Timber-Built Property?

    Yes, you can secure a mortgage on a timber-built property, but the options are more restricted compared to traditional brick-and-mortar homes. Fully timber constructions, such as log cabins, face greater scrutiny from lenders. Properties classified as ‘non-standard construction,’ which includes Swedish timber and chalet-style homes, may also be harder to finance.

    What Do Lenders Consider?

    When evaluating timber-built properties, lenders assess several factors:

    • Fire Risk: Timber properties may pose higher fire hazards compared to conventional builds.
    • Durability & Lifespan: The long-term viability of timber structures can affect lender confidence.
    • Resale Value: Properties that are harder to sell if repossessed can be a concern for lenders.
    • Maintenance Requirements: The upkeep of timber properties may influence lending decisions.

    What This Means for Borrowers and Investors

    For borrowers looking to purchase a timber-built home, the mortgage process may require a larger deposit and could involve higher interest rates. High street lenders often shy away from such properties, making it essential to consult with building societies or specialist lenders who have more flexible underwriting criteria. Engaging a knowledgeable mortgage broker can help navigate the limited options available and provide access to a wider range of lenders.

    Frequently Asked Questions

    What types of timber constructions are more likely to get approved?

    Properties like Swedish timber homes or chalet-style constructions may be more accepted than fully timber structures like log cabins, but they still fall under non-standard construction.

    Do I need a surveyor’s report for a timber-built property mortgage?

    Yes, a surveyor’s report is critical as it provides detailed insights into the property’s condition, which lenders will heavily rely on during the assessment process.

  • Record £108m Property Finance Boosts Mortgage Market

    Record £108m Property Finance Boosts Mortgage Market

    Word On The Street has achieved a remarkable milestone by arranging £108 million in property finance over the past year, marking a significant shift in the UK mortgage market. This achievement highlights the firm’s resilience amid ongoing economic challenges and reflects a growing demand for various types of property financing.

    TL;DR: Word On The Street facilitated £108 million in property finance, a 62% annual growth; this surge impacts landlords and investors seeking diverse financing options.

    What types of financing were arranged?

    The firm’s impressive total comprised a diverse range of financing options: 130 buy-to-let (BTL) cases, 82 bridging loans, 16 development finance projects, and 11 commercial mortgage cases. The average loan size was £462,637, indicating a robust appetite for property investment and development in the current market.

    Why is this growth significant for the mortgage market?

    This growth is noteworthy as it represents a 130% year-on-year increase in the number of cases facilitated by Word On The Street. The 62% rise in the total value of business reflects a broader trend in the mortgage market, where investors and landlords are increasingly seeking tailored financing solutions. With total revenue hitting £1.8 million, the firm has demonstrated that there is still substantial activity in property finance despite external economic pressures.

    What this means for landlords and investors

    The surge in property finance arranged by Word On The Street signals a positive outlook for landlords and investors. With various financing options available, including BTL and bridging loans, there is potential for growth in property portfolios. Investors should consider this trend as a signal to explore financing opportunities that align with their investment strategies. Additionally, brokers can use these insights to better serve clients seeking diverse mortgage solutions.

    Frequently asked questions

    What factors contributed to the growth in property finance?

    The growth can be attributed to a strong demand for diverse financing options, as well as the firm’s ability to navigate challenges in the market without distraction.

    How can I take advantage of these financing trends?

    Landlords and investors should explore various financing options, such as buy-to-let and bridging loans, to enhance their property portfolios and take advantage of market opportunities.